Free NewsletterPro Login

Warning: Undefined variable $stocks in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 448

Warning: foreach() argument must be of type array|object, null given in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 448

Warning: Undefined variable $funds in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 472

Warning: foreach() argument must be of type array|object, null given in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 472
/* the link was here */
×
Free investor livestream — Nov 17

How To Use ChatGPT & Claude To Research Stocks Like A Pro

01
The prompt we use to break down any stock
02
How to fact-check what AI tells you
03
How to compare two stocks in minutes

Argentina's Peso Just Had Its Biggest Drop In Eight Weeks

Published Jun 10, 2026
Share:
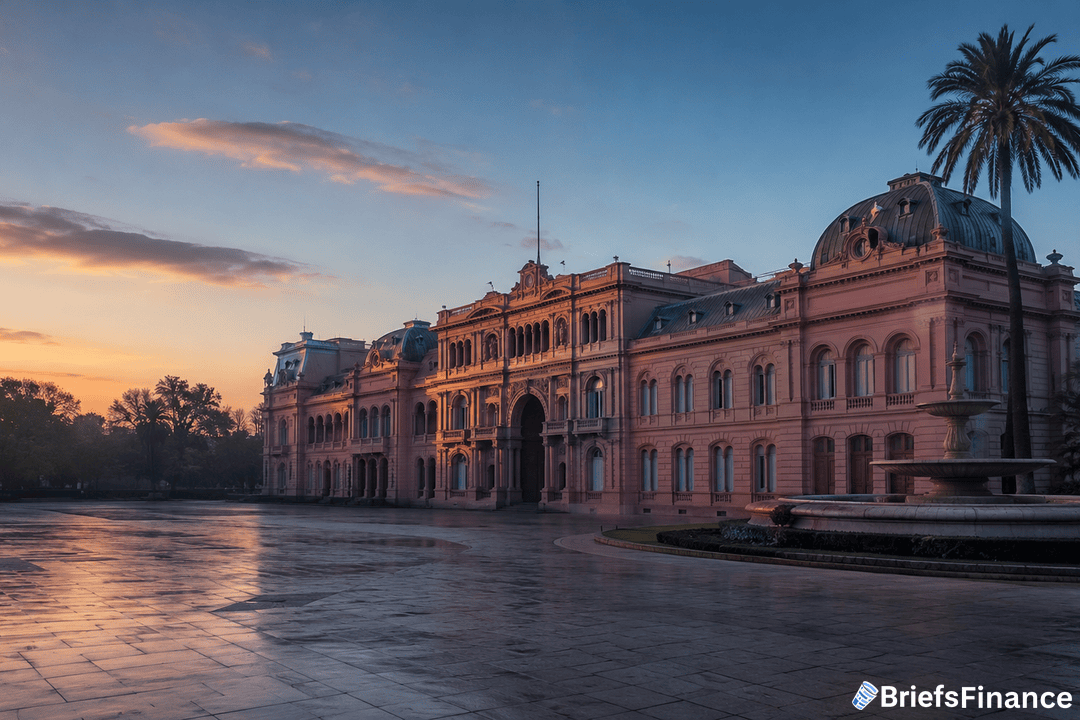
The Pink House (Casa Rosada) in Buenos Aires, Argentina, is seen at sunrise with a palm tree and a fountain in the foreground, and the BriefsFinance logo in the corner.
Summary:
  • The peso slid to about 1,442 per dollar, its worst drop since the post-election selloff in late October.
  • The fall came after President Javier Milei loosened his grip and let the currency trade more freely.
  • Argentina's central bank reserves recently hit their highest level since 2019.

Milei spent months stockpiling dollars to steady Argentina's shaky finances, and it worked well enough that reserves climbed to a seven-year high. Then he eased his grip on the peso, and the currency had its worst stretch since the country's October elections.

Why The Peso Fell

Argentina lets the peso trade inside a currency band, which is just a floor and ceiling the government sets and defends.

Investors had grown more cautious in recent weeks, and when people get nervous about a currency, they tend to move their money into dollars instead.

That buying pushed the peso to about 1,442 per dollar and toward the weak end of its band, leaving it down roughly 21% over the past year.

We translate global money moves like this into plain English every morning in Market Briefs - five minutes a day, and you get a free investing masterclass when you join.

Letting The Peso Float On Its Own

Letting a currency trade freely is like taking the training wheels off a bike, where the first wobble doesn't mean the rider can't make it work.

Milei is betting Argentina is finally steady enough to handle the swings, and the reserves back him up after reaching their highest level since 2019.

Reserves are simply the dollars a central bank keeps on hand, and they act as a cushion when a currency comes under pressure.

High inflation is still a problem at around 32% a year, though that is a steep drop from the nearly 300% pace the country saw back in 2024.

The Bigger Backstory

The peso has been shaky since a run on the currency began last fall, when locals rushed to swap pesos for dollars before they lost more value.

Milei's party did better than expected in October's midterm elections, which bought the government some room to ease its tight controls.

To make the shift smoother, the government has been slowly widening the peso's band in step with inflation, giving the currency a bit more room each month.

Argentina also leaned on a $20 billion loan from the International Monetary Fund last year, the global lender that steps in when countries hit financial trouble. Economy Minister Luis Caputo has ruled out a sudden devaluation, saying the current exchange-rate system will stay in place.

What To Watch

Whether this week's slide is a one-off wobble or the start of a longer drift toward the bottom of the band.

As one of the most closely watched emerging markets, Argentina's next move will ripple through stocks, bonds, and the price of everything locals buy.

Reserves are the cushion, and as long as they hold, Milei has room to let the peso find its own level. Eight weeks of calm just ended in one.

If you want global market reads like this before your coffee gets cold, join 350,000+ investors reading Market Briefs and grab a 45-minute investing course on the way in.

Disclosure

Recent News

1 2 3 … 116

Get Market Briefs delivered to your inbox every morning for free!

No fluff. No noise. No politics. Just finance news you can read in 5 minutes.

Blogs

November 2, 2026
Credit Utilization: How Paying Down Cards Can Help Your Score
  • Credit utilization is your card balances divided by your credit limits, checked overall and card by card.
  • Lower is generally better, and Experian says the effect becomes more noticeable around 30%.
  • Paying down balances and keeping new charges off your cards are the main ways to lower it.
Read More
November 2, 2026
How to Calculate Your Net Worth, With a Worked Example
  • Net worth is what you own minus what you owe, and it can be negative early on.
  • Use today's value for your assets and today's payoff balances for your debts.
  • Recalculate on the same date each quarter or year, since the trend matters more than the starting number.
Read More
November 2, 2026
How to Get Out of Debt on a Low Income, Step by Step
  • List every debt with its balance, APR, minimum and due date, then pause new charges.
  • An extra $50 a month on a $3,000 card at 22% cuts the payoff from about 44 months to about 26.
  • If nothing is left over, call your lenders and a nonprofit credit counselor, and avoid anyone who charges fees before settling debt.
Read More
November 2, 2026
How to Save Money on a Low Income, With a Budget Example
  • Saving 10% of a $2,000 paycheck is $200 a month, which reaches a first $2,000 in 10 months.
  • Set the transfer for payday and keep the money in a separate savings account.
  • Lower your biggest bills, cancel unused subscriptions and check programs like Lifeline and the EITC.
Read More
November 2, 2026
How to Budget With an Irregular Income, Even in Lean Months
  • Build your budget on your lowest recent month, not your average, so slow months don't leave you short.
  • Pay yourself a fixed salary from a holding account, and keep extra from good months as a cushion.
  • If no one withholds tax from your pay, set tax money aside every month.
Read More
November 2, 2026
How to Track Your Spending in 15 Minutes a Week
  • Start with last month's bank and card statements, receipts and any cash purchases.
  • Sort every purchase into a few groups that match your budget, like groceries and eating out.
  • Spend about 15 minutes each week adding purchases, checking each group and picking one change.
Read More
November 2, 2026
Should You Invest or Pay Off Debt? How to Decide
  • Card interest is a cost you can see ahead of time, while investing returns can go up or down.
  • A $3,000 card balance at 24% costs about $60 in interest in the first month.
  • Check whether you have a cushion, how high your rate is, whether your employer offers a match and how you'd handle a market drop.
Read More
November 2, 2026
Pay Yourself First: What It Means and How to Automate It
  • Paying yourself first means moving money to savings and investing on payday, before bills and spending.
  • The 75/15/10 split puts at least 10% toward savings and at least 15% toward investing.
  • Start smaller if money is tight, and automate the transfers so you only make the decision once.
Read More
November 2, 2026
What Is a Good Credit Score? Ranges and What Moves Yours
  • On the FICO scale, a good credit score is 670 to 739, and very good starts at 740.
  • Payment history (35%) and amounts owed (30%) are the two biggest parts of your score.
  • Paying every bill on time and paying down card balances are the two best places to start.
Read More
November 2, 2026
How to Lower Your Credit Card Interest Rate, With a Call Script
  • Before you call, have your APR, balance, card history, on-time record and any lower-rate offers ready.
  • Use the script to ask for a lower rate, then ask for a temporary cut or a hardship program if the answer is no.
  • On a $5,000 balance paid at $200 a month, dropping from 26.99% to 23.99% saves about $430 in interest.
Read More
1 2 3 … 31
Share via
Copy link