Free NewsletterPro Login

Warning: Undefined variable $stocks in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 448

Warning: foreach() argument must be of type array|object, null given in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 448

Warning: Undefined variable $funds in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 472

Warning: foreach() argument must be of type array|object, null given in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 472
/* the link was here */
×
Free investor livestream — Nov 17

How To Use ChatGPT & Claude To Research Stocks Like A Pro

01
The prompt we use to break down any stock
02
How to fact-check what AI tells you
03
How to compare two stocks in minutes

Builders Slash Prices to Move Homes, June Sales Edge Higher

Published Jul 24, 2026
Share:
Summary:
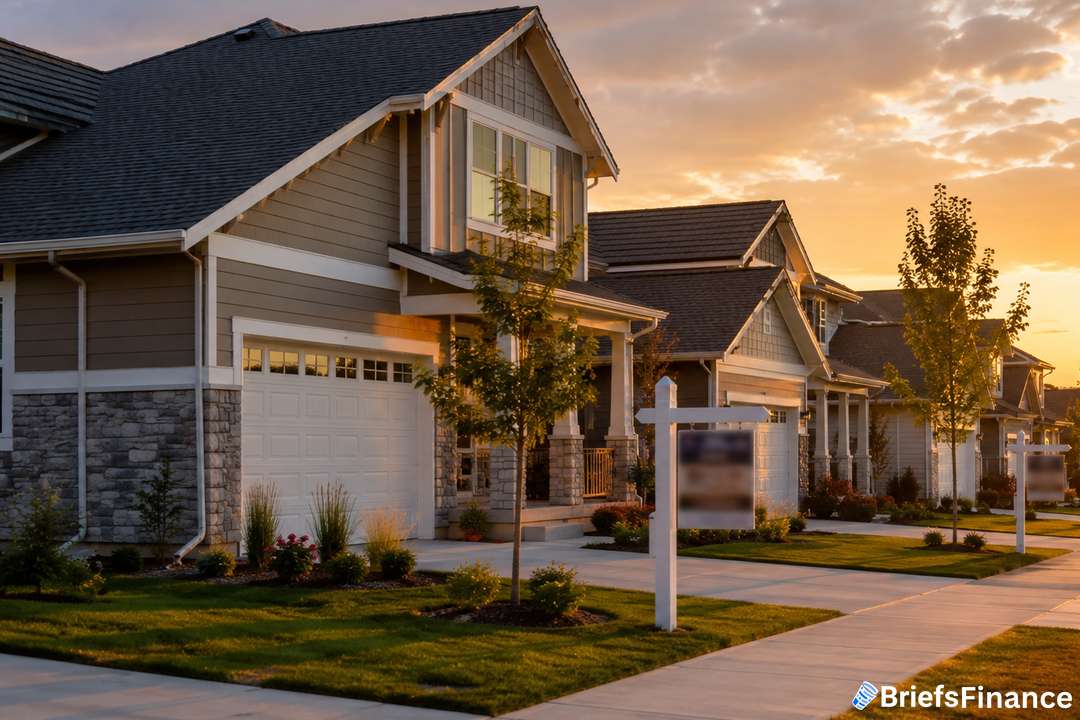
  • Sales of newly built single-family homes rose 1.6% in June, the first increase in three months.
  • Builders reduced the median new-home sale price by 2.7% compared to last year, bringing it to $398,300, as they offered incentives to lure buyers.
  • Purchases in the southern U.S., the nation's largest housing market, climbed 9.9% to 412,000 units, the best showing since November.

What the Numbers Actually Show

After three straight months of falling sales, something shifted in June. The government reported that new-home sales hit an annualized rate of 628,000 last month. That was better than the 607,000 economists had predicted.

But let's be clear about what drove that number. Builders are not suddenly seeing a flood of eager buyers with easy credit. Mortgage rates are still high, and consumer sentiment is subdued. What changed is that builders got aggressive with their pricing.

That is the kind of cut that gets attention. Builders are offering discounts, covering costs, and using incentives just to move houses off their lots. It worked for at least one month.

The Catch Behind the Improvement

Even with the sales bump, there were still 485,000 new homes on the market. At the current sales pace, that is a 9.3-month supply. For context, anything above six months usually means the market favors buyers, not sellers.

Builders have been slowing construction to avoid flooding the market further. They pulled back on "spec homes" - houses built without a signed buyer contract. D.R. Horton, a homebuilding giant focusing on starter homes, recently cut its sales guidance for 2026.

Get the market news that matters in a five-minute read with Market Briefs, our free daily newsletter

The government report itself came with a wide confidence band. According to the Census Bureau, with 90% confidence, the true change in sales could have ranged anywhere between a 13.2% decline and a 16.4% gain.

Stuart Paul, an economist at Bloomberg Economics, said: "New home sales quickened in June and a revision to May's print painted a slightly better picture than the initial release. But demand remains too soft to absorb inventories. We expect home prices to stay pressured throughout the year ahead as builders offer discounts and concessions to unload the excess of inventories."

The current glut of new homes is a direct consequence of the rapid rise in mortgage rates over the past two years. Builders had accelerated construction when rates were low, but the Federal Reserve's tightening campaign pushed borrowing costs to levels not seen in decades, stifling demand. As a result, many builders are now sitting on unsold inventory and are forced to offer price cuts and incentives - such as rate buydowns or covering closing costs - to attract the few buyers still in the market. This dynamic is unlikely to change until rates decline or incomes catch up to home prices.

What It Means for Your Portfolio

The big question is whether this pricing strategy can hold. Builders are in a bind. They need to sell homes to keep cash flowing, but cutting prices too much eats into their profit per house.

That is why you are seeing discounts rather than outright fire sales. They are trying to thread a needle between moving inventory and protecting margins.

For investors, this matters in two ways. First, homebuilder stocks have been under pressure as the market adjusted to higher rates. If builders have to keep discounting, their earnings could take a hit.

D.R. Horton's lowered guidance is a clue that analysts are watching this closely. Second, the housing market is a big part of the broader economy. When new-home sales are sluggish, it ripples through lumber, appliances, furniture, and even local jobs.

A bump in June is welcome, but it does not signal a boom.

The realistic outlook is more of the same. Expect builders to keep offering deals to move homes. Expect prices to stay flat or soften a little more through the rest of the year. And expect the market to be choppy until mortgage rates come down or consumer confidence improves enough that buyers feel comfortable jumping in.

For anyone thinking about buying a new home, the next few months might offer some room to negotiate. Builders are motivated. That is good news for buyers. For your portfolio, just keep an eye on whether those discounts start cutting into builder earnings - because that is where the real story will show up next.

Join Market Briefs, our free daily newsletter, for a quick daily rundown of the markets
Disclosure

Recent News

1 2 3 … 116

Get Market Briefs delivered to your inbox every morning for free!

No fluff. No noise. No politics. Just finance news you can read in 5 minutes.

Blogs

November 2, 2026
Credit Utilization: How Paying Down Cards Can Help Your Score
  • Credit utilization is your card balances divided by your credit limits, checked overall and card by card.
  • Lower is generally better, and Experian says the effect becomes more noticeable around 30%.
  • Paying down balances and keeping new charges off your cards are the main ways to lower it.
Read More
November 2, 2026
How to Calculate Your Net Worth, With a Worked Example
  • Net worth is what you own minus what you owe, and it can be negative early on.
  • Use today's value for your assets and today's payoff balances for your debts.
  • Recalculate on the same date each quarter or year, since the trend matters more than the starting number.
Read More
November 2, 2026
How to Get Out of Debt on a Low Income, Step by Step
  • List every debt with its balance, APR, minimum and due date, then pause new charges.
  • An extra $50 a month on a $3,000 card at 22% cuts the payoff from about 44 months to about 26.
  • If nothing is left over, call your lenders and a nonprofit credit counselor, and avoid anyone who charges fees before settling debt.
Read More
November 2, 2026
How to Save Money on a Low Income, With a Budget Example
  • Saving 10% of a $2,000 paycheck is $200 a month, which reaches a first $2,000 in 10 months.
  • Set the transfer for payday and keep the money in a separate savings account.
  • Lower your biggest bills, cancel unused subscriptions and check programs like Lifeline and the EITC.
Read More
November 2, 2026
How to Budget With an Irregular Income, Even in Lean Months
  • Build your budget on your lowest recent month, not your average, so slow months don't leave you short.
  • Pay yourself a fixed salary from a holding account, and keep extra from good months as a cushion.
  • If no one withholds tax from your pay, set tax money aside every month.
Read More
November 2, 2026
How to Track Your Spending in 15 Minutes a Week
  • Start with last month's bank and card statements, receipts and any cash purchases.
  • Sort every purchase into a few groups that match your budget, like groceries and eating out.
  • Spend about 15 minutes each week adding purchases, checking each group and picking one change.
Read More
November 2, 2026
Should You Invest or Pay Off Debt? How to Decide
  • Card interest is a cost you can see ahead of time, while investing returns can go up or down.
  • A $3,000 card balance at 24% costs about $60 in interest in the first month.
  • Check whether you have a cushion, how high your rate is, whether your employer offers a match and how you'd handle a market drop.
Read More
November 2, 2026
Pay Yourself First: What It Means and How to Automate It
  • Paying yourself first means moving money to savings and investing on payday, before bills and spending.
  • The 75/15/10 split puts at least 10% toward savings and at least 15% toward investing.
  • Start smaller if money is tight, and automate the transfers so you only make the decision once.
Read More
November 2, 2026
What Is a Good Credit Score? Ranges and What Moves Yours
  • On the FICO scale, a good credit score is 670 to 739, and very good starts at 740.
  • Payment history (35%) and amounts owed (30%) are the two biggest parts of your score.
  • Paying every bill on time and paying down card balances are the two best places to start.
Read More
November 2, 2026
How to Lower Your Credit Card Interest Rate, With a Call Script
  • Before you call, have your APR, balance, card history, on-time record and any lower-rate offers ready.
  • Use the script to ask for a lower rate, then ask for a temporary cut or a hardship program if the answer is no.
  • On a $5,000 balance paid at $200 a month, dropping from 26.99% to 23.99% saves about $430 in interest.
Read More
1 2 3 … 31
Share via
Copy link