Free NewsletterPro Login

Low National Negative Equity Hides Risks in Sunbelt Markets Like Cape Coral

Published Jul 6, 2026
Share:
Summary:
  • Only 1.5% of U.S. homeowner mortgages had negative equity as of late May 2026, up from 1% a year earlier but well below the 23% peak in 2009.
  • Cape Coral‑Fort Myers, Florida, leads the largest metros with 11.1% of mortgages underwater.
  • Nearly half of all outstanding mortgages (49.9%) carry rates below 4%, which accelerates principal repayment and equity building.

Most U.S. homeowners are sitting on plenty of equity. National home prices remain near record highs, and millions of borrowers locked in ultra-low rates during the pandemic. But a handful of Sunbelt markets tell a different story. There, home prices have fallen sharply from their peaks, and recent buyers are getting squeezed.

To put the current situation in perspective, the negative equity rate peaked at 23% during the Great Recession in September 2009. Since then, a combination of rising home prices, conservative lending standards, and pandemic‑era stimulus has dramatically improved homeowner balance sheets. Many borrowers who bought before 2020 have seen their home values double or more, while those with low‑rate mortgages are paying down principal faster than standard amortization schedules.

This financial cushion means that even if home prices dip moderately, the vast majority of homeowners remain above water. However, the recent downturn in Sunbelt markets highlights the vulnerability of buyers who entered at the peak of the pandemic boom.

Why National Negative Equity Is Low

As housing experts explain, "Being underwater means you owe more on your mortgage than your home is worth." It is also called negative equity. The low national rate is sustained by three key factors.

Get your free investing masterclass bonus when you join Market Briefs, our free daily newsletter

First, home prices across the country are still close to their historic peaks. Second, many homeowners locked in ultra-low mortgage rates during the pandemic, which means they have been paying down principal more aggressively; as of Q1 2026, 49.9% of outstanding mortgages still have rates below 4%. Third, tighter lending standards after the housing crisis mean that most borrowers have substantial down payments and solid credit, reducing the risk of negative equity.

These Sunbelt Markets Are Most at Risk

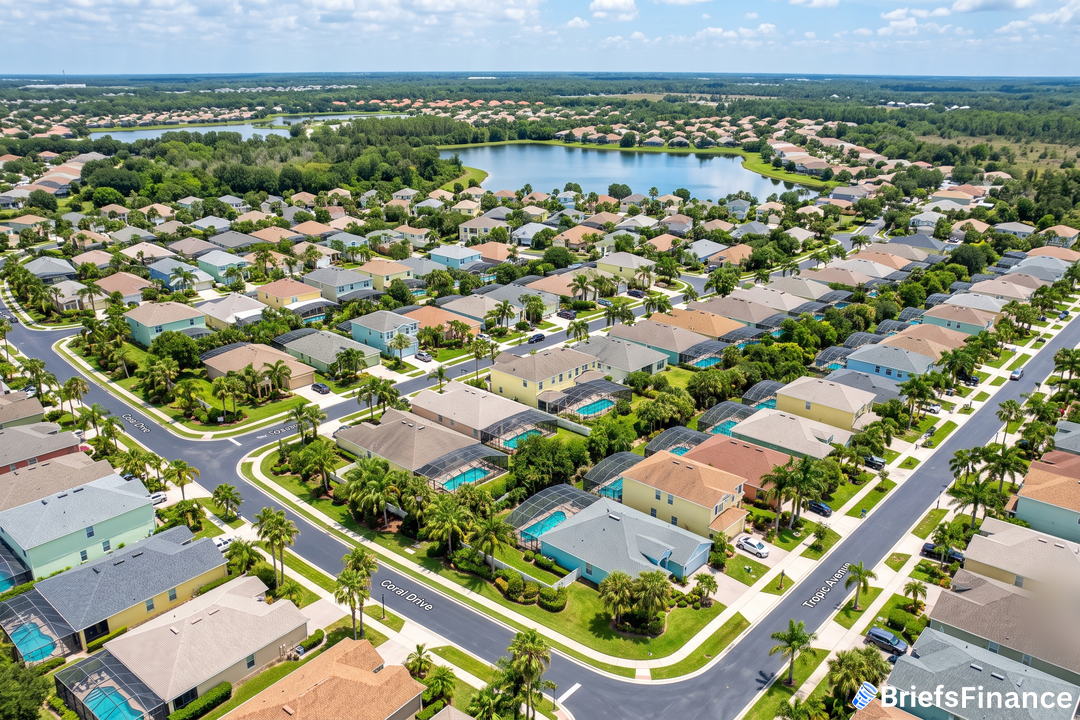
These cities saw huge home price jumps during the pandemic. Now they are giving back some of those gains. Home prices in Cape Coral‑Fort Myers have fallen 18.9% from their peak.

In Austin, the drop is even steeper at 27.3%. That hurts recent buyers most. Among Austin borrowers who bought in 2022, a striking 22.4% are underwater.

At the other end of the spectrum, Bridgeport, Connecticut, and San Jose, California, have just 0.1% of mortgages underwater. Boston, Los Angeles, and Hartford are at 0.2%. These markets never saw the same boom‑and‑bust pattern.

The pandemic-era housing boom was fueled by remote work, low interest rates, and demographic shifts toward warmer, more affordable regions. In Sunbelt cities like Cape Coral and Austin, prices surged as buyers competed for limited inventory. But once interest rates climbed and remote work patterns stabilized, demand cooled sharply, leaving recent purchasers with thin equity and heightened negative-equity risk.

ADVERTISEMENT

You can view the interactive version of the table covering all 100 metros analyzed by ICE Mortgage Technology here. While metros like Cape Coral (11.1%) and Austin (6.6%) have elevated underwater shares, these percentages remain far below the Great Financial Crisis peaks. In September 2009, Nevada saw 68% of borrowers underwater, Arizona 48%, and Florida 45%.

Currently, only recent borrowers from 2022-2025 are affected in these down markets. Furthermore, borrowers with thin equity - such as FHA and VA loans requiring as little as 3.5% down - are more likely to fall into negative equity. The key takeaway: if home prices continue to decline modestly in the Southwest, Southeast, and West, the underwater share among recent buyers will increase, but even then it won't approach the 2009-2010 levels.

Subscribe to Market Briefs, our free daily newsletter, and claim your bonus investing masterclass

Disclosure

Recent News

1 2 3 … 110

Get Market Briefs delivered to your inbox every morning for free!

No fluff. No noise. No politics. Just finance news you can read in 5 minutes.

Blogs

October 23, 2026
Are We in a Recession? 5 Threats to the Economy and Where the Money Is Moving
  • The S&P 500 is up about 13% this year, but without AI it's in a bear market, with nearly 40% of its companies down more than 20% for four months or longer.
  • Jackson, Briefs Finance's head of investing research, sees five threats: rising interest rates, sticky inflation, an economy propped up by AI, a struggling UK, and high oil prices.
  • The opportunities he's watching mostly sit outside the dollar: rising economies like Brazil and Indonesia, US-backed emerging market bonds paying 7% to 9%, and the shifts that fear creates.
Read More
October 16, 2026
How Boring Math Makes You Rich: The Briefs Money Spreadsheet, Explained
  • Briefs Money shows you what to do with every paycheck, and in what order: how much to spend, save, and invest, when to build an emergency fund, and which debt to pay off first.
  • The Climb to Wealth course walks you through the system step by step, and the Personal Finance Spreadsheet is where you track your own numbers.
  • Investing is one piece of building wealth. The system that gets money to your investments, and keeps it there, decides the outcome.
Read More
October 16, 2026
Common Investing Mistakes: Why a Stock Grade Is One Tool, Not the Whole Toolkit
  • The Briefs Score shows growth, income, and wealth preservation investors how well a stock fits their goal, with a separate letter grade for each one.
  • The most common mistake is treating the letter as an instruction. An A tells you a stock scores well for one goal, not that you should buy today.
  • Research works best as one input in a process you own. The grade shows how a stock stacks up. You supply the goal, the timeline, and the rules for being wrong.
Read More
October 16, 2026
How to Read a Company's Numbers Without a Finance Degree (Using Briefs Terminal)
  • Briefs Terminal lets you size up any public company in about ten minutes: what the stock costs, what it earns, how fast sales are growing, and what it pays you, all on one page.
  • It lines those numbers up against the company's closest competitors for you, so you can tell if a number is impressive or just average.
  • Below that are the income statement, balance sheet, and cash flow statement from the company's SEC filings, the latest news, and transcripts of its earnings calls.
Read More
October 16, 2026
What Type of Investor Am I? The Three Investor Archetypes, Explained
  • Briefs sorts its stock grades and monthly reports by three investor goals: growth, income, and wealth preservation. Pick yours and you know which report and which grade to read first.
  • Growth investors want stocks that beat the S&P 500. Income investors want to get paid in cash. Wealth preservation investors want stocks that hold up when the market drops.
  • The same stock can score an A- for one goal and a D- for another, so picking your goal comes before picking any stock.
Read More
October 16, 2026
How to Build a Stock Watchlist That Isn't Just Stocks You Heard About
  • A watchlist on Briefs Terminal lets you group stocks by the idea you're tracking and follow each one's price, one-day move, and 52-week high and low in one place.
  • Each list has its own name and description, so you always know why a stock is on it, and you can make as many lists as you have ideas.
  • The monthly growth, income, and wealth preservation reports under the Briefs Research tab hand you new themes to track that you didn't hear about online.
Read More
October 16, 2026
How to Choose an ETF That Matches Your Idea (Using the ETF Planning Tool)
  • The ETF planning tool takes an idea like "I want to invest in fast food companies," asks what you mean, and finds the ETFs that match, with the reasons, the holdings, and the sources.
  • Build a Plan then shows what your money could grow to in those ETFs over the years you choose, with conservative, expected, and optimistic estimates next to the S&P 500.
  • It gets you from an idea to an actual plan without researching dozens of companies one at a time.
Read More
October 16, 2026
Is This Stock a Good Buy? How to Use the Briefs Score to Tell If a Stock Fits the Way You Invest
  • The Briefs Score shows growth, income, and wealth preservation investors how well a stock fits their goal, with a separate letter grade for each one.
  • One stock can score very differently for each. Nvidia showed an A- for growth and a D- for income, because it grows fast and pays almost no dividend.
  • Seven sub scores under each grade show what earned the letter, so you can see exactly where a stock is strong or weak for your goal.
Read More
October 16, 2026
How to Tell an Asset From a Liability: The One Question to Ask Before You Buy Anything
  • The typical American household earned more in 2025 than in any year on record, yet only 30% of Americans say they could pay a surprise $1,000 bill from savings, so the problem isn't income but what the income gets spent on.
  • An asset puts money in your pocket and a liability takes money out, and the wealthy buy assets first, then let the assets pay for the fun stuff.
  • Before you buy anything, ask one question: does this put money in my pocket, or take money out of my pocket? Then you need a plan for the money you keep.
Read More
October 16, 2026
How to Build Your First $2,000 Emergency Fund and Wipe Out Every Debt Over 10%
  • Your first money goal isn't investing, it's $2,000 in its own account named Do Not Touch, built by moving 10% of every paycheck into it automatically.
  • More than a third of American adults couldn't cover a $400 surprise bill with cash or savings, according to the Federal Reserve, and that's how one bad day turns into years of credit card payments.
  • Once the $2,000 is there, attack every debt charging more than 10% interest, highest rate first, because you can't out-invest a 22% credit card so paying it off is the investment.
Read More
1 2 3 … 29
Share via
Copy link