What S&P found and why it matters
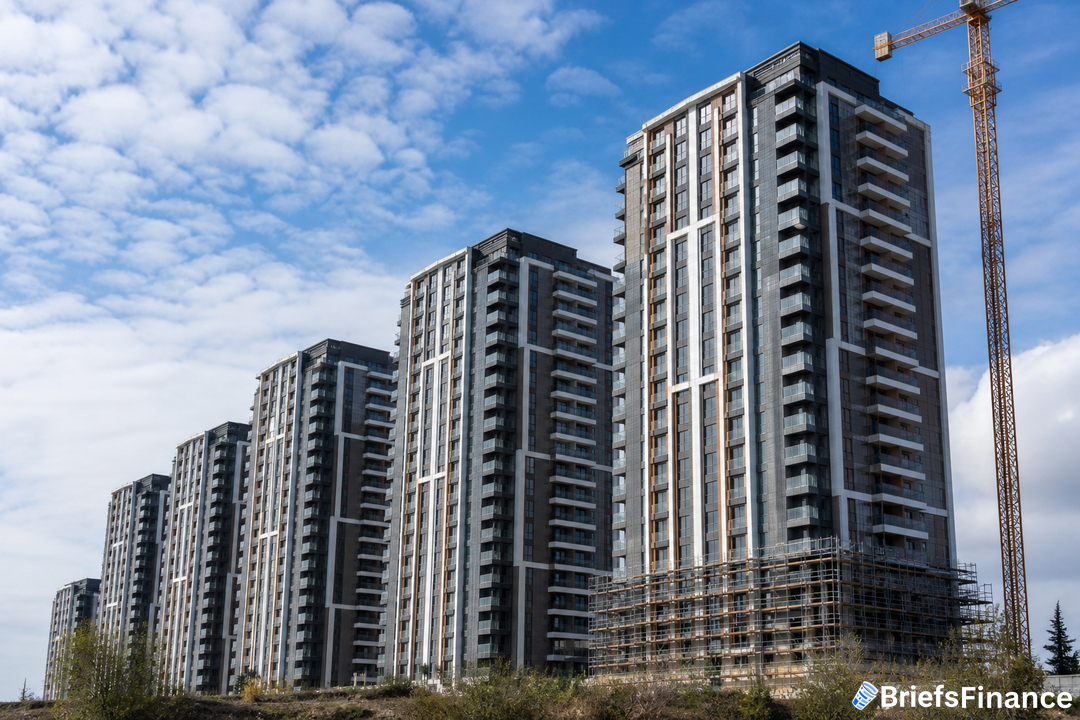
Analysts at S&P Global Ratings said in a Thursday report that China's multi-year housing downturn appears closer to its end. Their base case calls for residential prices to reach a trough in Q3 2028. They also expect China's largest cities, like Beijing and Shanghai, to show price recovery as early as next year.
S&P compared China's pullback with past housing busts in Japan, the U.S., and Spain. Two of the stabilizers that helped those markets - trimming supply and reducing corporate leverage - are now in play in China. The report noted that China's supply cutback is happening sooner and more forcefully than Japan's 1991 to 2014 episode.
On prices, China's homes are down 22% from a 2021 high, versus a 67% slide in Japan after a much bigger run-up. In the U.S., the housing slump tied to the financial crisis resulted in a 26% decline.
Policy shifts and how developers are reacting
In a Thursday phone call with CNBC, Edward Chan - S&P Global Ratings credit analyst and the report's author - said the outlook shifted due to two policy steps taken since February. Back then, S&P had flagged that heavy unsold inventory kept a recovery "out of reach."
First, Beijing in August tightened rules on developers' ability to sell homes before they are finished. Then in September, Premier Li Qiang said new measures were coming to steady the sector. Afterward, Beijing rolled out a mortgage-rate subsidy for first-time purchasers of homes priced below 1.5 million yuan ($220,000) and with floor space under 120 square meters (1291.67 square feet).
Chan said developers are likely to scale back land purchases and new projects, which may dent revenue but helps absorb excess supply. He added that over the next one to two years, ongoing supply reduction should be the key factor for stabilizing home prices.
Property downturns in large economies reach global growth eventually. Market Briefs covers that transmission free every weekday.
Inventory overhang, presales, and green shoots in cities
Despite a prolonged slump, S&P noted that 2026 marks the first year of inventory drawdown in China's housing market. The oversupply problem is large: Nomura estimated that in 2023 the stock of unfinished, pre-sold homes was roughly 20 times Country Garden's size as of end 2022. Country Garden had been China's biggest non-state developer by sales. Many developers, including Evergrande, leaned on selling apartments before completion, fueling debt and rapid expansion - with some buyers, like those in a Tianjin project near Beijing, waiting years for their pre-purchased units.
China's demand side is also getting a lift from mortgage subsidies and wealth effects tied to the artificial intelligence boom, according to S&P. City-level data lines up with that: Guotai Junan International's Chief Economist Hao Zhou said in a Thursday report that by Q4 this year, existing-home prices in China's top-tier markets could post their first uptick after the 2021 to 2023 downturn. Since March, he noted, the biggest cities have more often posted flat or rising prices than smaller ones. Shanghai's year-on-year drop has narrowed, while Beijing's existing home prices have steadied, up 1.4% from a January low.
Zhou pointed to Hangzhou - home to DeepSeek and Alibaba - as a standout. The city's new home sales index hit a record, and new home prices are only 14.2% below their peak, with smaller declines than most cities. He called the next three months a pivotal window, adding that so long as Shanghai, Shenzhen, and Guangzhou register no month-over-month declines through the November 2026 data, the upswing would surpass the 2024 to 2025 bounce in duration, marking a bottom for tier-one and offering a key signal for the wider market.
Demand signals and what it could mean for your money
Sustainability is the open question. Morgan Stanley equity analyst Stephen Cheung wrote Wednesday that the mortgage subsidy is likely to pull forward purchases rather than create a lot of new demand. He cited Bingshan data showing existing home sales across 25 cities climbed 50% year over year during the Oct. 1 to 6 holiday, accelerating from 20% growth in September.
For everyday investors, the story is a blend of shrinking supply, targeted policy support, and early-strength pockets in big cities. If the supply cut continues and tier-one prices hold their footing, that could reshape the outlook for China-related property exposure in indexes, funds, or developers tied to urban demand.
How long a correction runs matters more than how deep it goes. Join Market Briefs free and follow the cycle.