What's happening on the streets and in markets
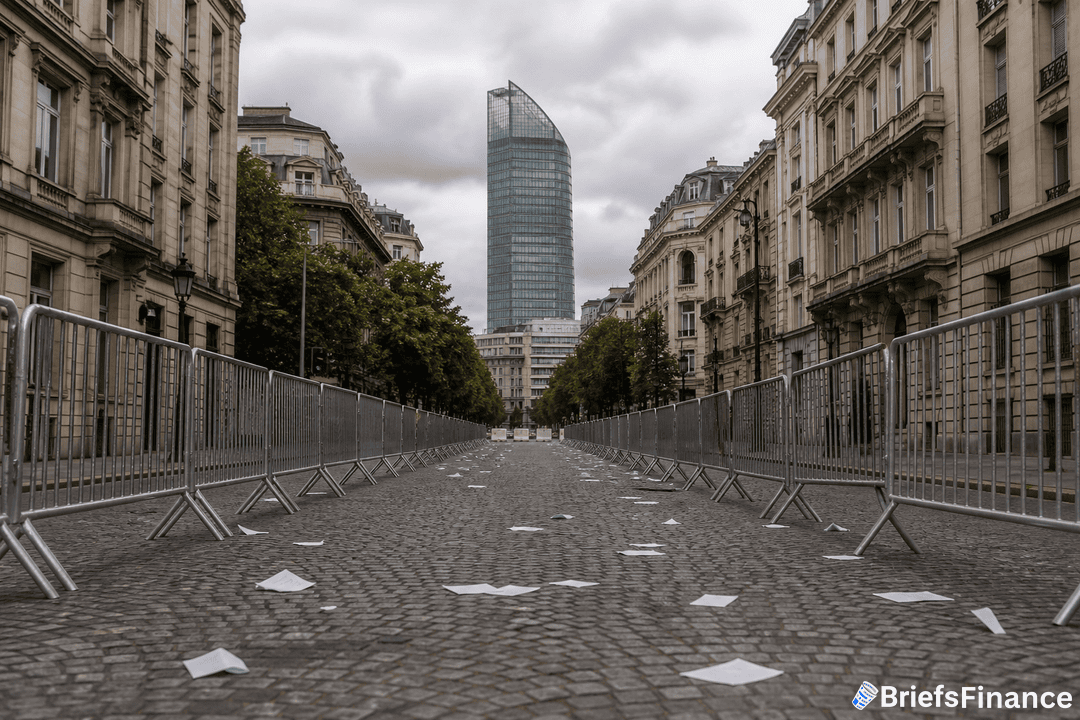
France is juggling unrest in the streets and a selloff in its bonds. Student-led demonstrations over education funding and university admissions have flared, with scattered violence over the past week and thousands of arrests. At the same time, investors are offloading French government debt as political risk and fiscal worries pile up.
You can see it in the price of borrowing. The extra yield investors demand to hold France's 10-year bonds over Germany's has swollen to more than double where it stood at the end of May. It briefly reached its widest since the 2011 euro-area debt crisis last week, eased a bit, then rose by about 12 basis points on Wednesday to 139 basis points.
The political pressure on the ECB
With the possibility of a government collapse and another deficit surge hanging over Paris, contenders for May's presidential race are turning up the heat on the ECB. Some want bond purchases and even debt cancellation. Far-left figure Jean-Luc Mélenchon ratcheted up the rhetoric, saying that if he wins he would seek treason charges against Bank of France Governor Emmanuel Moulin.
Marine Le Pen, the far-right leader who leads in polls, rolled out a plan on Tuesday to slash the deficit and simultaneously pressed for cheaper borrowing via ECB action. Speaking in Paris, she said, "It is vital to start a discussion with the ECB so that it intervenes to lighten the burden of rates as France takes back control," maintaining that this could release tens of billions of euros to support European investment in defense, sovereignty and climate adaptation.
Budget room is scarce, and that swelling deficit is exactly what is spooking investors.
Political unrest and bond stress together are what central bankers fear most. Market Briefs covers European risk free every weekday.
How central bankers are responding
Moulin pushed back on calls for intervention in a France Inter radio interview on Wednesday, drawing a comparison to "Trump's America with Jerome Powell." He added, "I refuse to be intimidated. I will continue to say what I think within the framework of my mandate, and to defend the institution that I preside."
He also underscored the ECB's remit: "The ECB is not there to deal with the fiscal problems of countries - it is there to fight inflation and have inflation around 2%." His bottom line right now: "The conditions are not met today for an intervention from the ECB." The ECB did buy bonds during the Covid shock, but with inflation still above target it has been moving the other way by lifting interest rates. There is also the Transmission Protection Instrument, set up in 2022 amid Italian market jitters, though it is unclear whether France would meet its activation criteria.
Where investors are testing limits and what it means for your money
Markets are probing how far they can go before policy makers blink, and scanning for any hint of ECB flexibility. "Markets have, however, learned that Europe and its financial institutions are nothing if not creative in the event of a crisis," said Jeremy Batstone-Carr, European strategist at Raymond James. "Just because limitations exist in prevailing terms and conditions does not mean that they cannot be tweaked."
On Tuesday, Finance Minister Roland Lescure said France remains far from needing ECB support, ahead of meetings with investors in London on Thursday, and stressed that today's backdrop differs from the sovereign crisis, when banks were at risk and some countries struggled to sell debt. For everyday investors, the takeaway is simple enough: politics are tugging at bond spreads, the deficit is the pressure point, and the ECB's rulebook is being quietly tested - all of which can filter into borrowing costs, savings rates, and the price of safety.
Whether the ECB intervenes will shape yields across the bloc. Join Market Briefs free and follow the test.