From a buttonwood tree to a pricing cartel
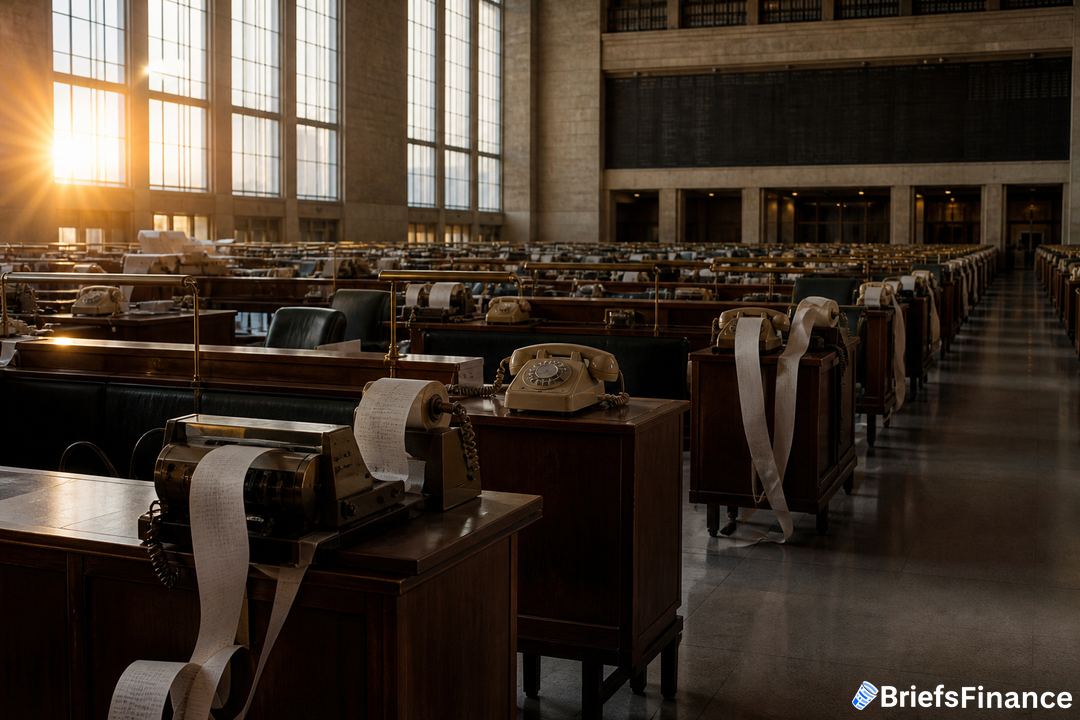
The long run of fixed commissions began on May 17, 1792, when 24 brokers, said to have gathered under a buttonwood tree on Wall Street, pledged to conduct transactions only for commissions, with no discounts allowed below a set minimum. That informal circle gradually transformed into what became the New York Stock Exchange. Early on, the pact gave legitimacy to securities dealing as a way to earn income and showed brokers could police themselves, which may have kept politicians from clamping down on stock trading.
Over time, the same structure hemmed the market in. As exchanges nationwide adopted fixed schedules, trading stayed costly, limiting broad public participation, and the clubby system among members dulled incentives to innovate in financial services.
The squeeze: institutions, regulators, and a rebel president
By the 1960s, big institutions like pension funds were central to volume and wanted cheaper trades. Firms wooed them with soft dollar perks such as research, which highlighted the gap with what individuals paid. A parallel venue also took hold: over-the-counter trading of exchange-listed shares, the third market, offering institutions a way around fixed fees.
Legal pressure mounted. In 1963, Silver v. New York Stock Exchange made clear that the Exchange was not shielded from antitrust law.
In 1968, the Justice Department questioned fixed rates as potentially anticompetitive and pushed the Securities and Exchange Commission to dig in. The NYSE pushed back, and for a while the SEC showed sympathy, though it grew sterner as the Exchange sought increases in the rate structure.
The fight went public on November 17, 1970, when NYSE president Robert Haack told the Economic Club of New York that commissions should be unfixed, arguing it would serve the Exchange over time. "I am concerned lest we bask solely in the glory of the past, and in the process become oblivious to emerging trends," he said. "The New York Stock Exchange, to put it crassly, no longer has the only game in town." The New York Times ran it on the front page.
Richard Jenrette countered, "It's a pretty sick patient to be performing major surgery on," and Loeb Rhoades CEO Clifford Michel called the move "ridiculous." Chairman Bernard "Bunny" Lasker told the Times that the board of governors - not its president - determined policy. Haack was not fired, but he left in 1971, and a reorganization eliminated the president's job until 1980.
Market structures evolve over time, and investors benefit from adapting their approach. We're hosting our first ever investor livestream on 11/17 to show you how to use ChatGPT and Claude to invest like a pro, hosted by Briefs Finance CEO Jaspreet Singh. Save your seat.
Merrill Lynch CEO Donald Regan aligned with Haack's position and pressed to end fixed commissions, criticizing Wall Street's capitalists for engaging in cartel-style coordination that kept rates inflexible. Merrill targeted the mass market more than its competitors did, and he was betting the firm would do well with more competition and higher volume. In Congress, John Moss convened hearings on fixed commissions and put forward legislation to abolish them. Regulators also nudged the door open: in 1971, with Chairman Hamer H. Budge at the helm, the SEC mandated negotiated commissions on trades exceeding 500,000 dollars, and in 1972 it cut that threshold to 300,000 dollars. The NYSE hired former SEC commissioner James Needham as chairman in 1972, and he warned as chair that he would fight a rapid overhaul "on the courthouse steps."
Momentum kept building. Ray Garrett became SEC chair in September 1973 and pushed for fully negotiated pricing. As a bridge, in April 1974, the cap was lifted for orders below 2,000 dollars, allowing commissions to be negotiated.
The SEC next abolished fixed rates entirely, effective May 1, 1975. It was deregulation of a private rulebook, not a rollback of government statutes.
What changed after May Day
The first months were muted. Many brokers kept prices near the old schedule, and some even raised what smaller investors paid. Over time, the shift was stark. Average commissions that had exceeded 80 cents a share in the early 1970s fell to about four cents in the early 21st century. Full service firms cut fees, discount brokers emerged to push prices down further, and online trading in the 1990s accelerated the drop.
Business models adapted. As ticket charges fell, fee-based arrangements became more common, and brokers widened their role from trade execution to advice and financial planning. Even Research magazine updated its tagline from "All a broker needs to succeed" to "Helping advisors help their clients." The feared collapse did not happen, but the industry had to change.
Why it still matters for your portfolio
May Day reset how Wall Street earned its keep, lowered the cost to buy and sell, and helped participation jump from about 15 percent of households in 1975 to roughly 50 percent three decades later. The bottom line: price competition reshaped brokerage and made trading cheaper, while firms shifted toward advice as commissions shrank.
New technologies offer investors fresh ways to gain a small but meaningful advantage. On 11/17, our CEO Jaspreet Singh goes live for our first ever investor livestream on how to use ChatGPT and Claude to invest like a pro. Register to join him.