Free NewsletterPro Login

Warning: Undefined variable $stocks in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 448

Warning: foreach() argument must be of type array|object, null given in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 448

Warning: Undefined variable $funds in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 472

Warning: foreach() argument must be of type array|object, null given in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 472
/* the link was here */
×
Free investor livestream — Nov 17

How To Use ChatGPT & Claude To Research Stocks Like A Pro

01
The prompt we use to break down any stock
02
How to fact-check what AI tells you
03
How to compare two stocks in minutes

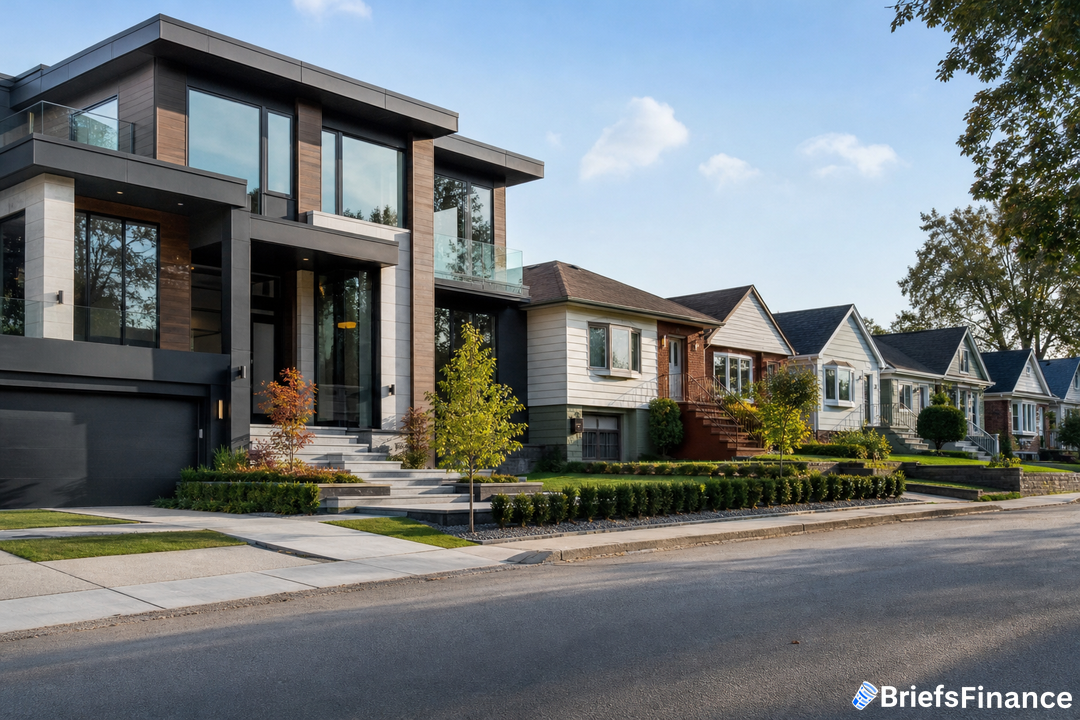
First American: Luxury Home Prices Pull Ahead Of Starter Homes In Most Cities

Published Oct 26, 2026
Share:
Summary:
  • First American's September Home Price Index shows top-tier homes gaining faster than entry-level homes in about 70% of large markets it tracks.
  • On an unadjusted, non-seasonal basis, nationwide prices were flat versus August, while September posted a 1.2% annual increase.
  • Starter-home prices kept climbing the fastest in Grand Rapids, Milwaukee, Cleveland, Philadelphia, and Chicago, with annual gains between 5.5% and 4.7%.

What the report measured

First American Data & Analytics' September Home Price Index tracks how prices change, not loan production or deal counts. It sorts each local market into three slices by its own price distribution: bottom third for starter, middle third, and top third for luxury.

Because those cutoffs are local, "luxury" is broader than multimillion-dollar listings and is not the same thing as the jumbo-loan segment.

What the data shows

Higher-end appreciation led the way in close to seven out of ten major markets in the study. Nationally, September prices were 1.2% above a year earlier, and on a non-seasonally adjusted basis they were flat compared with August. That September year-over-year print was the softest for any September since 2011, a period when prices were falling, yet all three tiers still posted positive annual gains.

Chief Economist Mark Fleming tied the split to borrowing power, saying, "Buyers at the lower end of the market tend to have less room to absorb higher monthly payments, while luxury buyers are generally less constrained by financing costs."

He added that limited affordable supply is propping up entry-level prices even as higher rates bite: "The long-term shortage of affordable homes continues to support starter-home prices, but today's affordability pressures are limiting how quickly those prices can rise."

When tracking home price trends across tiers, staying informed matters, so sign up for the free Market Briefs in five minutes.

Local snapshots that matter

Several Midwest and Northeast metros show how fast the entry rung is still moving. Among the 50 largest metros, starter-tier appreciation was strongest in Grand Rapids, Mich., at 5.5% year over year, with Milwaukee at 5.2%; Cleveland logged 5.1%; Philadelphia recorded 5%; and Chicago, 4.7%.

Tier-by-tier, the pattern flips depending on the city. In Chicago, luxury prices climbed 6.3% versus 4.7% for starters. Cleveland's luxury tier rose 5.3% compared with 5.1% for its starter tier.

In Grand Rapids and Philadelphia, the starter tier outran luxury, which increased 3.4% and 3.3%, respectively. Milwaukee's starter gain of 5.2% edged its 5.1% luxury rise.

Looking across the biggest markets, Chicago recorded the top annual gain at 5.1%, with New York posting 4.9%; Hartford, Conn., came in at 4.7%; and Cleveland and Milwaukee were both at 4.6%. Across the largest markets, Chicago posted the highest yearly increase at 5.1%, while New York logged 4.9%; Hartford, Conn., registered 4.7%; and both Cleveland and Milwaukee stood at 4.6%.

Why this is happening, and what it means for your portfolio

Fleming warned that higher mortgage rates can pinch both sides of the deal: "The recent increase in mortgage rates may further constrain affordability and strengthen the rate lock-in effect, limiting both the demand and the supply of homes for sale." Owners who stay put skip selling and also avoid taking on a pricier mortgage, which removes a buyer and a listing at the same time.

In plain English: a 1.2% national gain masks faster moves where entry-level stock is scarce. In markets where starter prices are rising at a multiple of the national pace, delaying a purchase can still mean chasing a higher number later. For lenders and investors following housing-linked names, the through-line is the same - match financing capacity and exposure to the specific tier that is actually moving in each local market.

Because housing markets change across different segments, get clear daily context with our free Market Briefs newsletter delivered in minutes.

Disclosure

Recent News

1 2 3 … 111

Get Market Briefs delivered to your inbox every morning for free!

No fluff. No noise. No politics. Just finance news you can read in 5 minutes.

Blogs

October 23, 2026
Are We in a Recession? 5 Threats to the Economy and Where the Money Is Moving
  • The S&P 500 is up about 13% this year, but without AI it's in a bear market, with nearly 40% of its companies down more than 20% for four months or longer.
  • Jackson, Briefs Finance's head of investing research, sees five threats: rising interest rates, sticky inflation, an economy propped up by AI, a struggling UK, and high oil prices.
  • The opportunities he's watching mostly sit outside the dollar: rising economies like Brazil and Indonesia, US-backed emerging market bonds paying 7% to 9%, and the shifts that fear creates.
Read More
October 16, 2026
How Boring Math Makes You Rich: The Briefs Money Spreadsheet, Explained
  • Briefs Money shows you what to do with every paycheck, and in what order: how much to spend, save, and invest, when to build an emergency fund, and which debt to pay off first.
  • The Climb to Wealth course walks you through the system step by step, and the Personal Finance Spreadsheet is where you track your own numbers.
  • Investing is one piece of building wealth. The system that gets money to your investments, and keeps it there, decides the outcome.
Read More
October 16, 2026
Common Investing Mistakes: Why a Stock Grade Is One Tool, Not the Whole Toolkit
  • The Briefs Score shows growth, income, and wealth preservation investors how well a stock fits their goal, with a separate letter grade for each one.
  • The most common mistake is treating the letter as an instruction. An A tells you a stock scores well for one goal, not that you should buy today.
  • Research works best as one input in a process you own. The grade shows how a stock stacks up. You supply the goal, the timeline, and the rules for being wrong.
Read More
October 16, 2026
How to Read a Company's Numbers Without a Finance Degree (Using Briefs Terminal)
  • Briefs Terminal lets you size up any public company in about ten minutes: what the stock costs, what it earns, how fast sales are growing, and what it pays you, all on one page.
  • It lines those numbers up against the company's closest competitors for you, so you can tell if a number is impressive or just average.
  • Below that are the income statement, balance sheet, and cash flow statement from the company's SEC filings, the latest news, and transcripts of its earnings calls.
Read More
October 16, 2026
What Type of Investor Am I? The Three Investor Archetypes, Explained
  • Briefs sorts its stock grades and monthly reports by three investor goals: growth, income, and wealth preservation. Pick yours and you know which report and which grade to read first.
  • Growth investors want stocks that beat the S&P 500. Income investors want to get paid in cash. Wealth preservation investors want stocks that hold up when the market drops.
  • The same stock can score an A- for one goal and a D- for another, so picking your goal comes before picking any stock.
Read More
October 16, 2026
How to Build a Stock Watchlist That Isn't Just Stocks You Heard About
  • A watchlist on Briefs Terminal lets you group stocks by the idea you're tracking and follow each one's price, one-day move, and 52-week high and low in one place.
  • Each list has its own name and description, so you always know why a stock is on it, and you can make as many lists as you have ideas.
  • The monthly growth, income, and wealth preservation reports under the Briefs Research tab hand you new themes to track that you didn't hear about online.
Read More
October 16, 2026
How to Choose an ETF That Matches Your Idea (Using the ETF Planning Tool)
  • The ETF planning tool takes an idea like "I want to invest in fast food companies," asks what you mean, and finds the ETFs that match, with the reasons, the holdings, and the sources.
  • Build a Plan then shows what your money could grow to in those ETFs over the years you choose, with conservative, expected, and optimistic estimates next to the S&P 500.
  • It gets you from an idea to an actual plan without researching dozens of companies one at a time.
Read More
October 16, 2026
Is This Stock a Good Buy? How to Use the Briefs Score to Tell If a Stock Fits the Way You Invest
  • The Briefs Score shows growth, income, and wealth preservation investors how well a stock fits their goal, with a separate letter grade for each one.
  • One stock can score very differently for each. Nvidia showed an A- for growth and a D- for income, because it grows fast and pays almost no dividend.
  • Seven sub scores under each grade show what earned the letter, so you can see exactly where a stock is strong or weak for your goal.
Read More
October 16, 2026
How to Tell an Asset From a Liability: The One Question to Ask Before You Buy Anything
  • The typical American household earned more in 2025 than in any year on record, yet only 30% of Americans say they could pay a surprise $1,000 bill from savings, so the problem isn't income but what the income gets spent on.
  • An asset puts money in your pocket and a liability takes money out, and the wealthy buy assets first, then let the assets pay for the fun stuff.
  • Before you buy anything, ask one question: does this put money in my pocket, or take money out of my pocket? Then you need a plan for the money you keep.
Read More
October 16, 2026
How to Build Your First $2,000 Emergency Fund and Wipe Out Every Debt Over 10%
  • Your first money goal isn't investing, it's $2,000 in its own account named Do Not Touch, built by moving 10% of every paycheck into it automatically.
  • More than a third of American adults couldn't cover a $400 surprise bill with cash or savings, according to the Federal Reserve, and that's how one bad day turns into years of credit card payments.
  • Once the $2,000 is there, attack every debt charging more than 10% interest, highest rate first, because you can't out-invest a 22% credit card so paying it off is the investment.
Read More
1 2 3 … 29
Share via
Copy link