Free NewsletterPro Login

Warning: Undefined variable $stocks in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 448

Warning: foreach() argument must be of type array|object, null given in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 448

Warning: Undefined variable $funds in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 472

Warning: foreach() argument must be of type array|object, null given in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 472
/* the link was here */
×
Free investor livestream — Nov 17

How To Use ChatGPT & Claude To Research Stocks Like A Pro

01
The prompt we use to break down any stock
02
How to fact-check what AI tells you
03
How to compare two stocks in minutes

Homebuilder Confidence Just Fell To 35 - Its Longest Slump Since 2012

Published Jun 15, 2026
Share:
Summary:
  • Builder confidence fell two points to 35 in June on the NAHB/Wells Fargo index.
  • It has stayed below 40 for 14 straight months, a stretch not seen since 2011-2012.
  • 35% of builders cut prices in June, and 62% offered sales incentives to close deals.

The U.S. is short about 1.2 million homes.

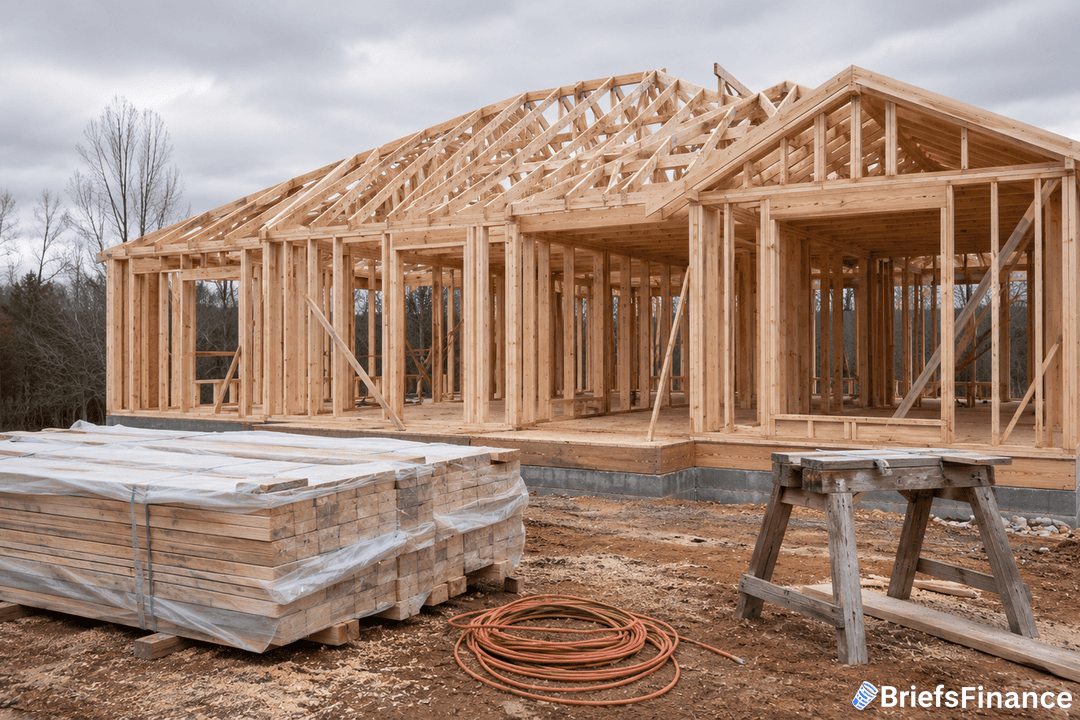
You would think builders would be racing to put up more. Instead, they are the most downbeat they have been since the last housing crash.

What The Numbers Say

Builders' view of the new-home market slipped to 35 this month, down two points. That score comes from the NAHB/Wells Fargo Housing Market Index.

The index is a monthly read on how builders feel. Above 50 means more of them see good conditions than bad.

At 35, the mood is clearly sour. And it has been sour for a long time.

The index has now sat below 40 for 14 months in a row. That is the worst stretch since the 2011-2012 housing crisis.

Back then, foreclosures were flooding the market. This slump has a different cause.

High rates and high costs, not a wave of defaults, are the problem now. The drop was broad this time, too.

The gauge for current sales fell to 38. The gauge for buyer traffic stayed weak at 25.

The gauge for sales over the next six months held at 45. So builders are not bracing for a deeper drop.

We break down what housing data means for your money in Market Briefs, and joining comes with a free investing masterclass.

Builders Are Cutting Prices To Move Homes

When buyers stay home, builders sweeten the deal. About 35% of builders cut prices in June, up from 32% in May.

The average cut was around 6%. On top of that, 62% leaned on sales perks to get deals done.

That share has topped 60% for 15 months straight. It shows how hard it is to close a sale right now.

Why are buyers holding back? High mortgage rates and high building costs are the main reasons.

Builders point a finger at red tape, too. NAHB economist Robert Dietz said rules, taxes and fees add more than 26% to the price of a new home.

Builder groups also want help from Washington. They are pushing a housing package now before the Senate.

They back bills to ease the labor shortage as well. Each one aims to make building cheaper.

They also want softer energy rules on new homes. The goal is to trim the cost of every build.

What To Watch

The pain is not even across the country. The South and West are the weakest, while the Northeast and Midwest hold up better.

On a three-month average, the West sits at just 27. The Northeast leads the pack near 44.

For investors, weak building points to tight supply ahead. That keeps pressure on home prices and rents, and it ripples through the wider economy.

It also weighs on homebuilder stocks. Their fortunes track how many homes get sold, and mortgage lenders feel it too.

The country needs more homes. Yet the people who build them say the math still does not work.

For a five-minute read on the economy every morning, sign up for Market Briefs and get a free 45-minute investing course as a bonus.

Disclosure

Recent News

1 2 3 … 116

Get Market Briefs delivered to your inbox every morning for free!

No fluff. No noise. No politics. Just finance news you can read in 5 minutes.

Blogs

November 2, 2026
Credit Utilization: How Paying Down Cards Can Help Your Score
  • Credit utilization is your card balances divided by your credit limits, checked overall and card by card.
  • Lower is generally better, and Experian says the effect becomes more noticeable around 30%.
  • Paying down balances and keeping new charges off your cards are the main ways to lower it.
Read More
November 2, 2026
How to Calculate Your Net Worth, With a Worked Example
  • Net worth is what you own minus what you owe, and it can be negative early on.
  • Use today's value for your assets and today's payoff balances for your debts.
  • Recalculate on the same date each quarter or year, since the trend matters more than the starting number.
Read More
November 2, 2026
How to Get Out of Debt on a Low Income, Step by Step
  • List every debt with its balance, APR, minimum and due date, then pause new charges.
  • An extra $50 a month on a $3,000 card at 22% cuts the payoff from about 44 months to about 26.
  • If nothing is left over, call your lenders and a nonprofit credit counselor, and avoid anyone who charges fees before settling debt.
Read More
November 2, 2026
How to Save Money on a Low Income, With a Budget Example
  • Saving 10% of a $2,000 paycheck is $200 a month, which reaches a first $2,000 in 10 months.
  • Set the transfer for payday and keep the money in a separate savings account.
  • Lower your biggest bills, cancel unused subscriptions and check programs like Lifeline and the EITC.
Read More
November 2, 2026
How to Budget With an Irregular Income, Even in Lean Months
  • Build your budget on your lowest recent month, not your average, so slow months don't leave you short.
  • Pay yourself a fixed salary from a holding account, and keep extra from good months as a cushion.
  • If no one withholds tax from your pay, set tax money aside every month.
Read More
November 2, 2026
How to Track Your Spending in 15 Minutes a Week
  • Start with last month's bank and card statements, receipts and any cash purchases.
  • Sort every purchase into a few groups that match your budget, like groceries and eating out.
  • Spend about 15 minutes each week adding purchases, checking each group and picking one change.
Read More
November 2, 2026
Should You Invest or Pay Off Debt? How to Decide
  • Card interest is a cost you can see ahead of time, while investing returns can go up or down.
  • A $3,000 card balance at 24% costs about $60 in interest in the first month.
  • Check whether you have a cushion, how high your rate is, whether your employer offers a match and how you'd handle a market drop.
Read More
November 2, 2026
Pay Yourself First: What It Means and How to Automate It
  • Paying yourself first means moving money to savings and investing on payday, before bills and spending.
  • The 75/15/10 split puts at least 10% toward savings and at least 15% toward investing.
  • Start smaller if money is tight, and automate the transfers so you only make the decision once.
Read More
November 2, 2026
What Is a Good Credit Score? Ranges and What Moves Yours
  • On the FICO scale, a good credit score is 670 to 739, and very good starts at 740.
  • Payment history (35%) and amounts owed (30%) are the two biggest parts of your score.
  • Paying every bill on time and paying down card balances are the two best places to start.
Read More
November 2, 2026
How to Lower Your Credit Card Interest Rate, With a Call Script
  • Before you call, have your APR, balance, card history, on-time record and any lower-rate offers ready.
  • Use the script to ask for a lower rate, then ask for a temporary cut or a hardship program if the answer is no.
  • On a $5,000 balance paid at $200 a month, dropping from 26.99% to 23.99% saves about $430 in interest.
Read More
1 2 3 … 31
Share via
Copy link