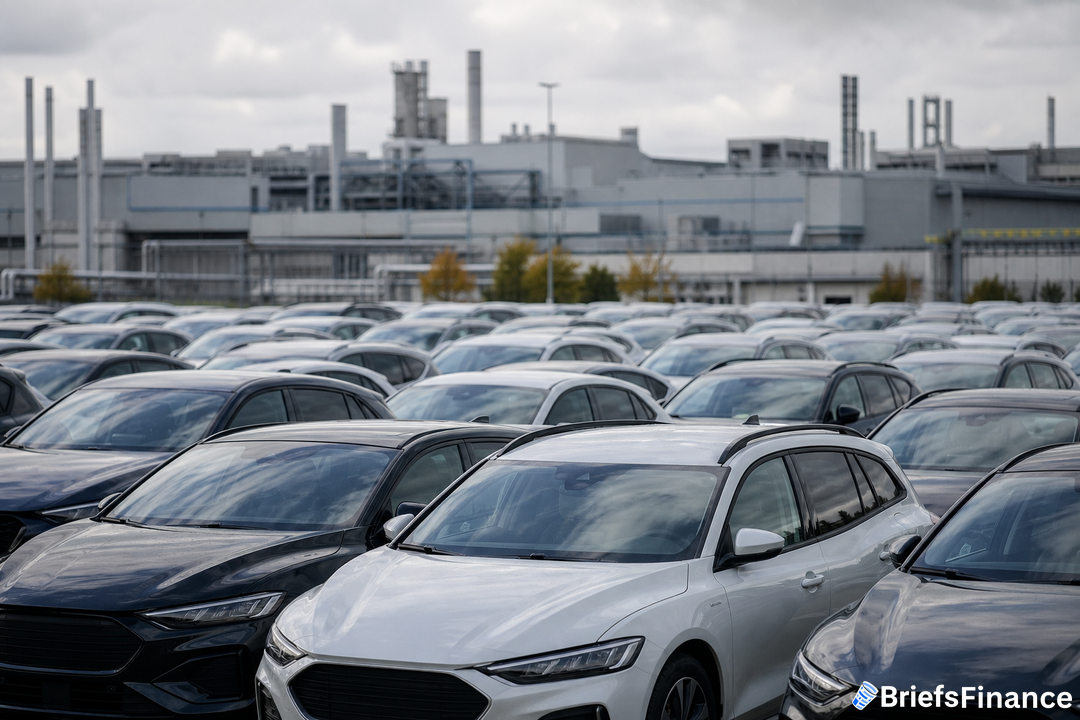
Q3 beat, with North America doing the heavy lifting
GM delivered adjusted earnings per share of $3.70, ahead of the $3.63 LSEG consensus. Revenue came in at $50.02 billion, topping the $48.7 billion estimate. Net income attributable to stockholders came in at $3.3 billion, about $2 billion higher than the same period a year earlier.
Adjusted EBIT registered $4.1 billion, with North America contributing $3.6 billion of that total. For comparison, the company's 2025 third quarter showed $48.59 billion in revenue, $1.3 billion in net income attributable to stockholders, and $2.80 in adjusted EPS.
Analysts called the print solid, while questioning whether rising costs and pressure on vehicle pricing could restrain earnings growth next year.
Guidance and buybacks: tighter range, more cash, bigger return
The updated forecast targets adjusted EBIT between $14.5 billion and $15.5 billion, adjusted EPS of $12.75 to $13.75, plus automotive adjusted free cash flow projected at $11.5 billion to $12.5 billion. By comparison, the July outlook called for adjusted EBIT of $14 billion to $16 billion, adjusted EPS of $12 to $14, and projected automotive adjusted free cash flow in a range of $9.5 billion to $11.5 billion.
GM finished a previously announced $6 billion buyback and launched a new multiyear $20 billion repurchase authorization. Management did not specify a timeline to complete it. According to LSEG, analysts were looking for a $13.41 full-year EPS midpoint, versus GM's updated $13.25.
When corporate updates prompt more questions than answers, stay informed with the free daily Market Briefs newsletter
Costs, inflation and what management is watching
GM indicated its commodity inflation costs should land near $2 billion, which is the upper bound of its earlier guidance. That reflects higher logistics expenses and pricier DRAM chips. The company expects gross tariff costs at the low end of its $2.5 billion to $3.5 billion range, and warranty costs at the high end of the $1 billion to $1.5 billion range.
"Our fourth quarter's going to be down sequentially. ... I think the fact that we're able to hold our guidance in the face of that late inflationary pressure in the year is another sign of the GM team executing really well," CFO Paul Jacobson told CNBC. He also said pricing is roughly flat as inflation rises, and that GM will assess consumer conditions next year before deciding on price increases above normal levels.
"GM is performing well, and we are working hard to continue our momentum despite growing inflationary pressures through strategic investments in new products and services, and through improved quality and operating efficiency," CEO Mary Barra wrote to shareholders.
GM added that the costs tied to the all-electric vehicle pullback announced last year are "substantially completed." Beginning in the latter half of last year, it booked $11.2 billion in associated charges and, through the third quarter, had paid $4.6 billion of the $7.4 billion cash portion.
The bottom line for your portfolio
Investors got a clean Q3 beat and a larger buyback, while the stock slipped roughly 5% as the outlook underwhelmed versus expectations. Management is flagging inflation in commodities, logistics and DRAM, while tariff and warranty costs are trending within stated bands. Watch how those inputs filter into 2026 margins and whether flat pricing stays intact.
If you want clear context on earnings and corporate moves without the noise, sign up for the free daily Market Briefs newsletter