What Fitch is saying
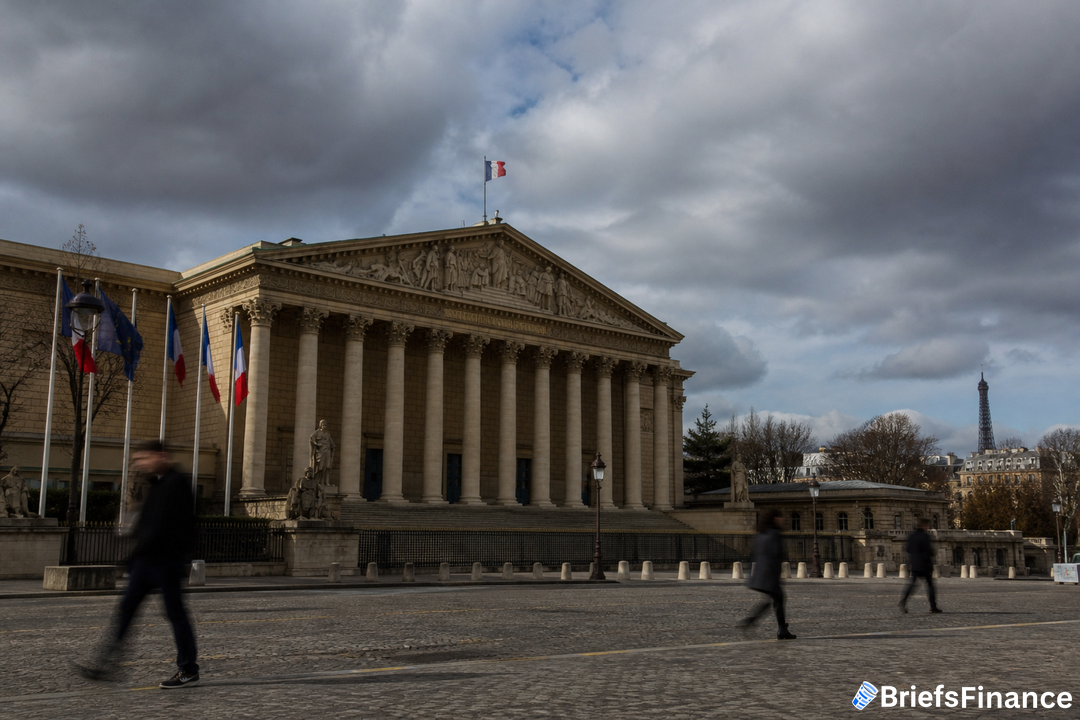
France's latest budget drive is more than cosmetic. This week, in an interview, Federico Barriga-Salazar described Roland Lescure's bid to reduce next year's deficit to 5% of output as "substantial." He added, "The whole challenges of the fiscal story are still there, but it's significant enough that it would create a bit of a short circuit if it didn't happen." As he put it, "It is big, it is important. The question mark is whether it gets approved in its current state."
The proposal rolled out earlier this month includes €43 billion ($48.2 billion) in steps to cut the deficit and soothe financial-market concerns. On the current stress points, he said Wednesday, "Where we are today, it's a fiscal problem," and, "It's not a financing problem."
Rating agency language is a leading indicator for borrowing costs. Market Briefs covers sovereign credit free every morning.
Politics, spreads, and promises
Investor jitters are visible in bond pricing: the extra yield on French 10-year debt over Germany's recently rose to its highest level since 2011. Against that uneasy backdrop, the sticking point is political approval, not market access.
Days before the interview, far-right presidential contender Marine Le Pen set out goals to narrow the deficit to 3.7% of GDP in 2027 and to 2.2% five years later. Barriga-Salazar noted that the outline aligns with France's formal European Union commitments, while emphasizing the lack of execution detail. "There's not enough detail to show that this can be achieved within the next two to three years," he said. "There would need to be much more ironed out."
What could happen next and why it matters for your money
If a budget standoff drags on, Barriga-Salazar predicted the government is prepared to break precedent and use an ordinance to push it through. "I think they've prepared the ground for this," he said. "They cannot function very well without a budget, so I think this looks like a very likely outcome."
On the ratings backdrop, Fitch cut France to A+ last year. Scope and S&P now sit at the same level, while Moody's remains higher and could update its view later this month. Because of the typical six-month review gap, Fitch's next assessment is likely in early 2027, near the presidential election, when "It's already clear that the fiscal situation in France will be much more difficult." For your wallet, the things to watch are simple enough: whether the budget actually gets passed and where French-German spreads go next, since both can filter into borrowing costs and the performance of funds holding French government bonds.
When analysts use words like substantial, bond markets listen. Get the free Market Briefs daily newsletter and follow it.