What moved prices
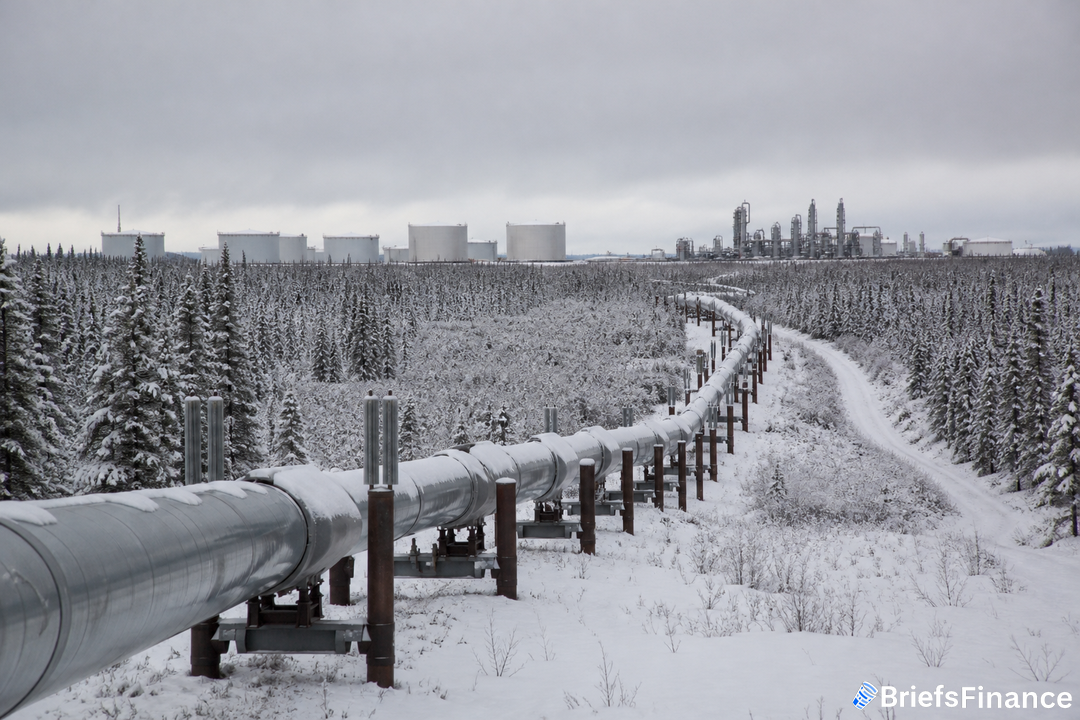
Canadian heavy barrels have slid relative to US benchmarks. According to Modern Commodities and General Index, Western Canadian Select in Alberta was quoted early Tuesday at a $31.70-per-barrel deficit to the monthly average WTI futures price, the largest since November 2018.
Cold Lake crude is showing the same strain on the US Gulf Coast, where the discount sits at $23.10, matching an eight year extreme. That undercuts realized prices for many producers even with global crude now above $100 a barrel.
Why the discount is widening
This time the pressure is coming from abroad, not from pipeline constraints at home. Disruptions from the Iran war have driven tanker rates sharply higher, constricting overseas shipping capacity, with the squeeze most acute along the US Gulf Coast, where a large share of Canadian crude arrives.
At the same time, a greater volume of Venezuelan heavy barrels is heading to US refineries and a smaller share to Asia, intensifying competition on the Gulf and widening the Canadian discount there. The wider spread in the Gulf has pushed more barrels to load off the Trans Mountain Pipeline to Vancouver. Tanker exports there hit a record last month. Freight for Aframax ships serving Trans Mountain has increased, but not as fast as the supertanker rates out of the Gulf, and the shorter trip to East Asia keeps Vancouver liftings comparatively cheaper.
Market shifts create opportunities for investors who adapt with smarter tools and timing. We're hosting our first ever investor livestream on 11/17 to show you how to use ChatGPT and Claude to invest like a pro, hosted by Briefs Finance CEO Jaspreet Singh. Save your seat.
Who benefits, who feels the pinch, and what to watch
A wider differential dents cash flow for many heavy oil producers, though operators with refining capacity such as Suncor Energy Inc. can benefit from cheaper feedstock. Imperial Oil Ltd., an ExxonMobil Holdings Corp. unit, said last week it expects weaker Canadian pricing to persist through the fourth quarter.
For context, the last major blowout came in late 2018, when the discount neared $50 a barrel as output outpaced pipeline capacity. Alberta responded by imposing caps on output for the biggest producers, and over the next two years those curbs were gradually rolled back and eliminated. In contrast, the current widening owes more to global dynamics than to any domestic pipeline shortfall. The bottom line: if your portfolio leans into Canadian heavy producers, keep an eye on tanker costs and heavy supply on the Gulf Coast.
A little extra insight can make a big difference in long term investment outcomes. On 11/17, our CEO Jaspreet Singh goes live for our first ever investor livestream on how to use ChatGPT and Claude to invest like a pro. Register to join him.