Free NewsletterPro Login

Free Live Investors Workshop

Seats limited

Tue, Sep 29.

The dollar is losing value.

Here’s how investors can still profit.

Hosted By

Jaspreet Singh

Founder, Briefs Finance

X

Warning: Undefined variable $stocks in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 448

Warning: foreach() argument must be of type array|object, null given in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 448

Warning: Undefined variable $funds in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 472

Warning: foreach() argument must be of type array|object, null given in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 472
/* the link was here */

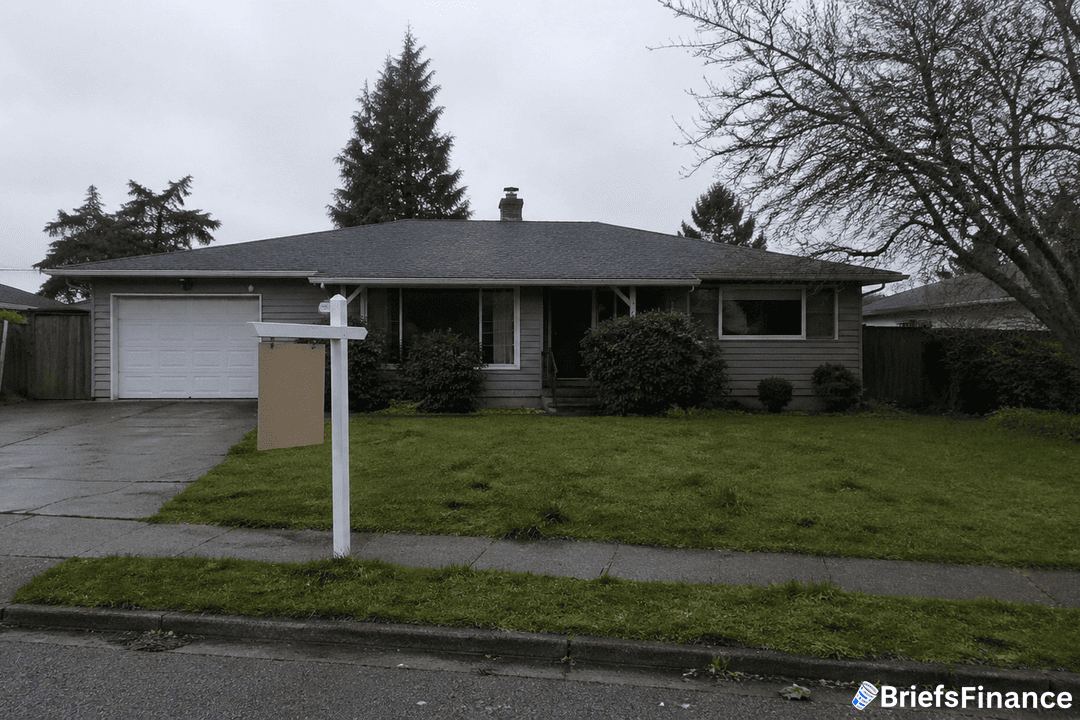
Zillow Just Cut Its 2026 Home Sales Forecast To Near Flat

Published Apr 25, 2026
Share:
Summary:
  • Zillow cut its 2026 existing-home sales forecast to about 0.5% growth.
  • The rate lock-in effect is still pushing down transaction volume.
  • Home prices are set to stay roughly flat for the year.

Zillow just told home buyers and sellers what many already feel. 2026 is going to be a slow year for home sales.

The firm cut its full-year existing-home sales forecast to about 0.5% growth. That is close to flat.

It also sees home prices staying near level for the year.

What Is Driving The Cut

The main driver is the rate lock-in effect. Most homeowners have mortgages at rates well below today's level.

That means they do not want to sell and take out a new, higher-rate loan. So fewer homes come to market.

Low listings mean low sales, even when buyer interest picks up.

Inventory Is Rising, But Slowly

Inventory is up from a year ago. That is good news.

But the rise is from a very low base. The number of homes on the market is still well below what was normal in 2018 or 2019.

A slow rise in listings does not fix the sales drought. It just chips at it.

The Price Picture

Flat prices are a shift from the big gains of 2020 and 2021. They also reflect a market that cannot decide which way to go.

Some cities are seeing small price cuts. Others are still climbing.

The national number masks a wide spread between regions.

The Regional Split

Zillow flagged two clear trends.

The Sunbelt is softening. Places like Austin, Tampa, and Phoenix got too much supply and see prices stall or dip.

The Midwest is more steady. Cities like Columbus, Des Moines, and Indianapolis have less supply and tighter buyer demand.

For sellers, the Midwest looks safer. For buyers, the Sunbelt gives more choice.

What Buyers Should Know

For buyers, the Zillow read is neither great nor bad. Rates are still high, prices are stable, and the choice is growing.

The best buy windows tend to open when rates drift down. If rates fall in late 2026, buyer power can jump fast.

Until then, the buyer has time. There is less pressure to act now than at any point since 2020.

What Sellers Should Know

For sellers, the math is tougher. Flat prices mean small gains, and a slow market means longer sale times.

Homes that show well and price right still sell. Homes that are priced aggressive can sit for months.

A big price cut at the start often beats a slow chain of small ones.

What Could Break The Slowdown

Two forces could lift the 2026 outlook. The first is a real drop in mortgage rates. The second is a wave of new listings from owners who give up on waiting.

Fannie Mae is forecasting sub-6% rates by year-end. If that plays out, the Zillow forecast starts to look too low.

Listings are also starting to rise, even at high rates. If that keeps going, sales can pick up even before rates fall much.

The Builder Angle

Home builders have a split view. Flat prices are tough on new construction margins, but rising inventory helps them clear backlogs.

Most big builders are trimming new starts for 2026. That limits how much extra supply hits the market.

It also keeps prices from falling much further.

Worth Noting

A near-flat year for home sales is not a crash. But it is not a thaw either.

The housing market is still stuck in its mix of high rates and low listings.

Zillow just put a number on that fact.
Disclosure

Recent News

1 2 3 80

Get Market Briefs delivered to your inbox every morning for free!

No fluff. No noise. No politics. Just finance news you can read in 5 minutes.

Blogs

September 17, 2026
Why America Bailed Out the Yen: The Japan Carry Trade, the Dollar and Your Mortgage Rate
  • In July 2026 the US sent money to steady the yen because Japan is the largest foreign owner of US debt, and Washington needs Japan to keep lending.
  • For decades the Japan carry trade let Wall Street borrow yen at essentially 0% and pour it into US stocks, real estate and Treasuries, and rising Japanese rates are shutting that off.
  • A weaker yen means fewer buyers for the dollar and for US debt, which pushes Treasury rates up and drags mortgage, car loan and credit card rates up with them.
Read More
September 16, 2026
Treasury Yields Are Spiking Because Lenders Are Backing Away From U.S. Debt
  • The U.S. is paying its highest 30-year borrowing rate in about two decades because its biggest lenders, the Fed, foreign governments, and banks, are all pulling back from Treasuries.
  • Every mortgage, car loan, credit card, and business loan is priced off the 10-year Treasury yield, so when Washington pays more to borrow, so do you.
  • With about $40 trillion of debt against a $32 trillion economy, the country either outgrows its debt or slides into a doom loop, and investors need a plan for both.
Read More
September 15, 2026
Fiat Currency Runs on Trust, and the World Just Stopped Trusting the Dollar
  • Gold has overtaken US treasuries as the world's top reserve asset, and central banks are now buying less US debt and more gold.
  • The US dollar is a fiat currency, meaning it's backed by a promise rather than gold, so it loses value when fewer countries want to hold it.
  • Whether the US economy or its national debt grows faster from here decides which assets stand to benefit next.
Read More
September 14, 2026
Why RAM Prices Are Soaring - and Where the Money Is Moving
  • Memory chips - the RAM inside phones, laptops, fridges, and trucks - are in a shortage Tim Cook called a 100-year flood, and some memory prices have climbed about 90% in a single quarter.
  • Four forces hit at once: AI demand, a production shutdown in 2023, build times that push any fix to 2028 at the earliest, and a bombed helium plant in Qatar.
  • The last two supply shocks ended in aggressive Fed rate hikes and market drops of around 45% and 20%, and this time Washington is spending heavily to bring memory production home.
Read More
September 11, 2026
How Is the Economy Doing? Washington Says It's Fixed, but the Numbers Don't Agree
  • Treasury Secretary Scott Bessent says the economy is fixed because lower earners' incomes are now rising faster than top earners'.
  • The Atlanta Fed and Bank of America show different numbers, and Hilton, Marriott, and McDonald's can't agree on what they're seeing either.
  • Whichever side is right, the economy is built to make investors rich, and inflation is how it does it.
Read More
September 10, 2026
US National Debt Hits $40 Trillion: Why the Economy Hasn't Collapsed Yet
  • The US national debt crossed $40 trillion in 2026 and is growing faster than the economy. The debt to GDP ratio now sits at 125%, the highest outside the pandemic and higher than World War II.
  • On September 9, 2026, Treasury Secretary Scott Bessent rolled out an emergency plan for the government to lend money to itself. Ray Dalio now says the dollar has roughly three years before real pain.
  • Empires rarely default. They debase. Since 1971, median household income grew about 8x while houses grew 17x and the S&P 500 grew 360x, so investors got richer while workers fell behind.
Read More
September 9, 2026
Your 401k Is Fueling the AI Bubble
  • About $10 trillion of 401k money sits in a $77 trillion stock market, mostly through target date funds and S&P 500 funds. Roughly 30% of every S&P 500 dollar lands in five AI-heavy tech stocks.
  • Four bubble signals run hotter today than before the 2000 crash: top-ten concentration, tech's share of the index, the Buffett Indicator, and how much of the market index funds own.
  • You only lock in an AI bubble loss if you sell. The 2022, 2020, 2008, and 2000 crashes were all buying windows for long-term investors, and the US-China AI race means government money could keep flowing in.
Read More
September 9, 2026
What Is Wealth Preservation? How To Protect Your Money From Anything
  • Wealth preservation is an investing strategy built around keeping the money you've already made instead of chasing growth.
  • It leans on assets that hold steady when markets fall - gold, Treasury bonds, and companies that keep earning through wars, crashes, and pandemics.
  • The tradeoff is real: you give up some upside, and the two key numbers to check are maximum drawdown and correlation to the market.
Read More
September 8, 2026
Why Is Everything So Expensive? Why Prices May Never Come Back Down
  • Official inflation is 3.4% and prices are up 32% since 2020, but rent (41%), gas (47%), car insurance (64%) and ground beef (79%) all outran the 28% median wage.
  • The Federal Reserve targets 2% inflation on purpose. Rising prices push extra dollars to investors and shrink the real cost of a $40 trillion national debt.
  • Investors who simply owned the S&P 500 gained about 150% over the same six years, and the Fed's September 16 decision will show whether it protects the dollar or the economy first.
Read More
September 7, 2026
The U.S. Housing Market Just Flipped: Renting a Home Now Beats Buying One
  • The US is in a buyer's market in 41 of the 50 largest metro areas, but prices sit near record highs and mortgage rates are close to 7%.
  • The same median house costs 27% more than it did in 2021 while the monthly payment costs 90% more, and incomes rose a little more than 10%.
  • A 2008-style crash is not showing up in the data, so the pressure is landing on buyers instead of prices.
Read More
1 2 3 27
Share via
Copy link