What happened
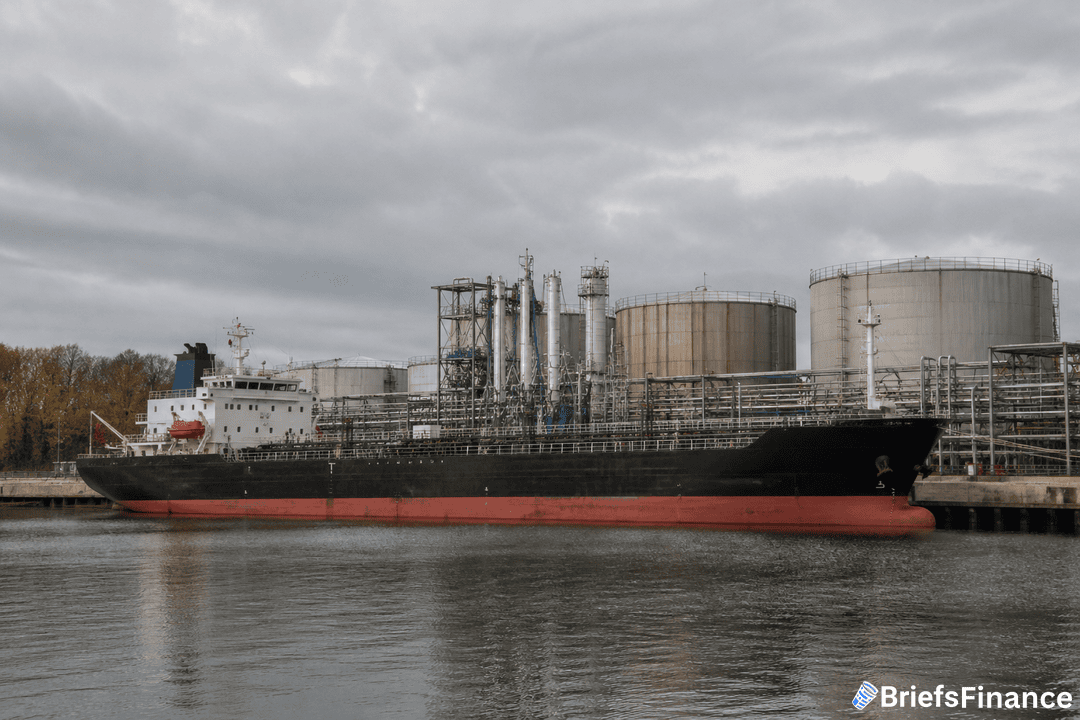
In the first third of October, Russia's outbound refined-fuel flows thinned. Bloomberg's read of Vortexa tracking shows total seaborne oil products at 979,000 barrels per day over the first 10 days, with diesel and gasoil leading the declines.
Diesel and gasoil exports were 11% below September's daily average. Within that, diesel shipments ran at 146,000 barrels per day, the lowest level in Vortexa data back to early 2016. Naphtha eased 4% to 299,000, while fuel oil edged up to 534,000.
No gasoline or jet fuel departures were observed through Oct. 10. As with most ship-tracking tallies, volumes may be revised as new details land.
When energy and trade headlines can affect portfolios, sign up for the free Market Briefs newsletter for five-minute clarity.
Why exports moved
Moscow curbed diesel sales abroad to protect domestic supply after repeated Ukrainian strikes on Russian refineries crimped output. That domestic-first tilt showed up most clearly in diesel and gasoil.
Russian officials signaled they will keep bringing in some gasoline at least through the end of the year. A rebound in exports is not a sure thing, as Ukrainian President Volodymyr Zelenskyy has pledged to restart strikes on Russian facilities in retaliation for ongoing attacks on Ukraine.
What changed on Oct. 11 and what it means for your portfolio
Shipments could begin to pick up later in the month. Deliveries to the US could take two to three weeks, since contracts still have to be finalized.
The bottom line: watch diesel spreads and tanker movements. Any uptick in Russian product supply can filter through to product prices and refining margins, which in turn can sway energy equities and transport costs.
Markets and supply chains move in ways that matter to everyday investors, so get daily context with Market Briefs in minutes.