What the firms are doing
Two of the fastest market builders in finance want to do for computing power what futures did for oil. Jump Trading is standing up a dedicated desk that will put its own balance sheet to work, taking positions and carrying the risk. The team, which includes Affaan Mustafa and Alejandro Soumah Fernandez, both from compute startup Ito Markets Inc., plans to operate across over-the-counter transactions, perpetual futures and prediction wagers.
Jump plans to make markets in compute futures in development at CME and Silicon Data, and it is eyeing competing contracts from Intercontinental Exchange and Ornn. CME's launch still needs regulatory approval. Jump holds investments in both Silicon Data and Ornn. As Dave Olsen, Jump's president and chief investment officer, put it, the firm expects to "trade against those different pockets of demand and supply," adding, "We think there's a real opportunity for us."
DRW is setting up to trade compute via three groups running different playbooks, two existing and one new. Founder Don Wilson, who co-founded Compute Exchange and invested in Silicon Data, said DRW has so far devoted more energy to indexes and derivatives than to buying or selling compute directly, describing its spot activity as "dabbling." For now, DRW plans to trade Silicon Data's products and has not yet chosen other compute contracts. "Right now, the market is very opaque, and there isn't good price transparency," Wilson said.
How this market takes shape
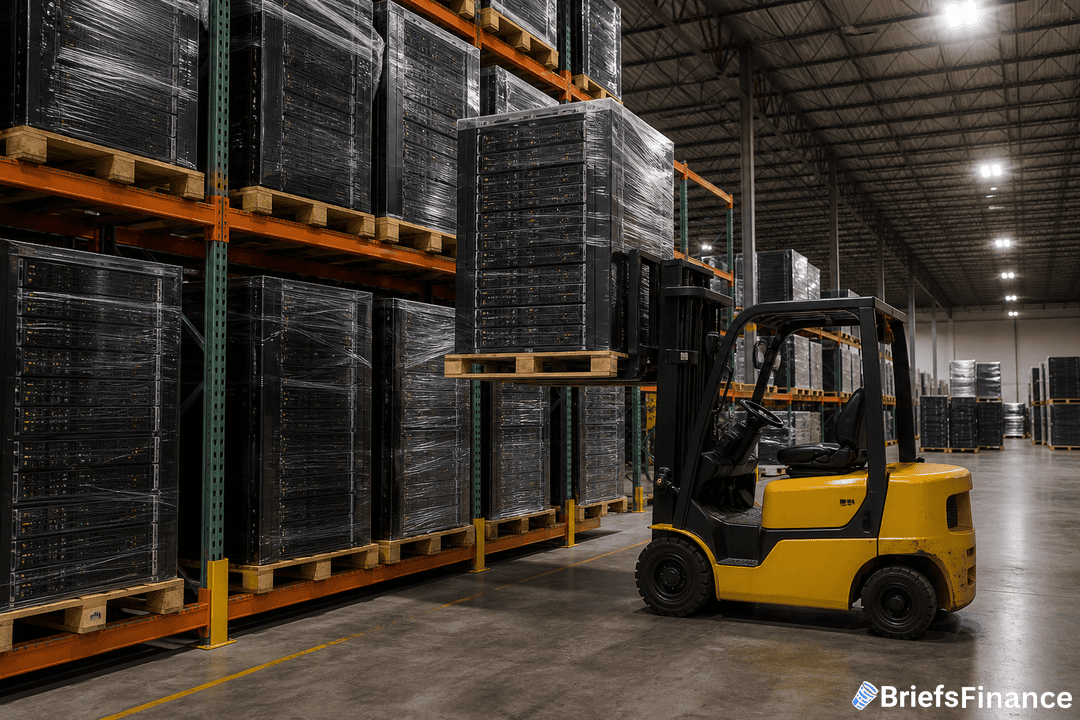
Exchanges and trading firms are trying to turn negotiated deals for GPU time into a hedging market for compute prices. CME and Silicon Data are developing futures tied to what it costs per hour to rent Nvidia H100 and B200 chips, and Intercontinental Exchange is backing products that cite Ornn's indexes. CME's planned futures are slated to rest on Silicon Data's indexes. FalconX has already carried out an OTC swap linked to future compute pricing.
The pitch is familiar for Jump and DRW, which both leaned into crypto early when trading was splintered and big banks largely watched. Compute shows similar quirks. A buyer may need a specific Nvidia model in a specific region and cluster while equivalent GPUs sit idle elsewhere. Identical chips can clear at different prices depending on location, provider and configuration, so a futures index might not perfectly mirror a buyer's needs. In Olsen's words, aligning those is "a little bit of a leap of faith."
When new ideas reshape markets, a clear daily recap helps, sign up for the free Market Briefs newsletter today
Unlike oil or copper, unused GPU hours vanish. That means the classic store-and-sell trade is hard to replicate. Olsen said that makes buy, store and sell later against a higher futures price tough in compute.
Why now, and what could follow
A sharp slide in AI infrastructure shares and bonds has put fresh focus on whether income from compute can cover the buildout. CoreWeave's stocks and bonds have dropped as investors debate if future AI revenue can service the debt used to construct data centers. Carmen Li, Silicon Data's founder, said recent volatility bolsters the case for hedging GPU rental costs.
According to Boston Consulting Group, the AI compute market may climb to $2.3 trillion by 2030. Larry Fink, BlackRock chief executive, has argued that a new asset class may emerge in the form of futures on computing power.
Wilson said continued AI infrastructure investment requires someone to take the risk on future compute prices and customer payment. "Futures give providers a way to manage price risk without relying on multiyear commitments from AI startups," he said. A forward curve could clarify residual exposure in longer-term capacity deals and give traders more ways to manage it. If liquidity builds, he also expects algorithmic strategies to show up.
What this could mean for your portfolio
Market makers may get there before the end users. Olsen expects hedge funds, dealers and other trading firms to dominate futures activity for "a prolonged period" until AI labs, neoclouds and other large buyers see cash settled contracts line up with their procurement. "That will take some time," he said.
Both Jump and DRW argue that futures could mute price and credit risk in compute. SemiAnalysis data show rental prices for top-end chips can swing meaningfully quarter to quarter, pressuring AI startups and the lenders behind data centers. The bottom line: if compute futures mature, investors could gain a new way to hedge or get exposure to the cost side of AI infrastructure. But the market is still opaque, and many building blocks - from pricing indices to liquidity - are works in progress.
Staying informed about evolving market structures makes decision-making easier, so get quick context from the free Market Briefs delivered every weekday