Free NewsletterPro Login

Warning: Undefined variable $stocks in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 448

Warning: foreach() argument must be of type array|object, null given in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 448

Warning: Undefined variable $funds in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 472

Warning: foreach() argument must be of type array|object, null given in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 472
/* the link was here */
×
Free investor livestream — Nov 17

How To Use ChatGPT & Claude To Research Stocks Like A Pro

01
The prompt we use to break down any stock
02
How to fact-check what AI tells you
03
How to compare two stocks in minutes

The "Silver Tsunami" Could Flood U.S. Listings but Miss Starter Homes

Published Oct 5, 2026
Share:
Summary:
  • Realtor.com® estimates that between 2026 and 2036, 13.9 million homes now owned by boomers and the Silent Generation will stop being occupied by older owners.
  • Annual turnover is expected to rise from roughly 1.27 million in 2027 and approach 1.52 million by 2036; if 45% of the 2027 group shows up as listings, that by itself would return yearly listing totals to pre-pandemic norms, assuming nothing else changes.
  • The supply skews big: only about 380,000 have two bedrooms or fewer, nearly three quarters are three or four bedrooms, with millions more at five-plus.

The scale and shape of the release

Realtor.com®'s Generational Housing Succession report, released Monday, projects that 13.9 million homes now held by older owner-occupants will be freed up from 2026 through 2036. Across that window, activity steps up, starting near 1.27 million in 2027 and reaching 1.52 million by 2036. A quick back-of-the-envelope check illustrates the effect: if 45% of the homes slated for release in 2027 were listed for sale, that by itself would push annual listing totals back to pre-pandemic norms, assuming other factors stay the same.

That is welcome news for buyers who have been boxed out by thin inventory. It does not mean the market suddenly becomes balanced or cheap. In the words of Jiayi Xu, senior economist at Realtor.com, "We believe the softness will be real, though its effects will be uneven across segments and markets, not a uniform, nationwide correction."

What kinds of homes will hit the market

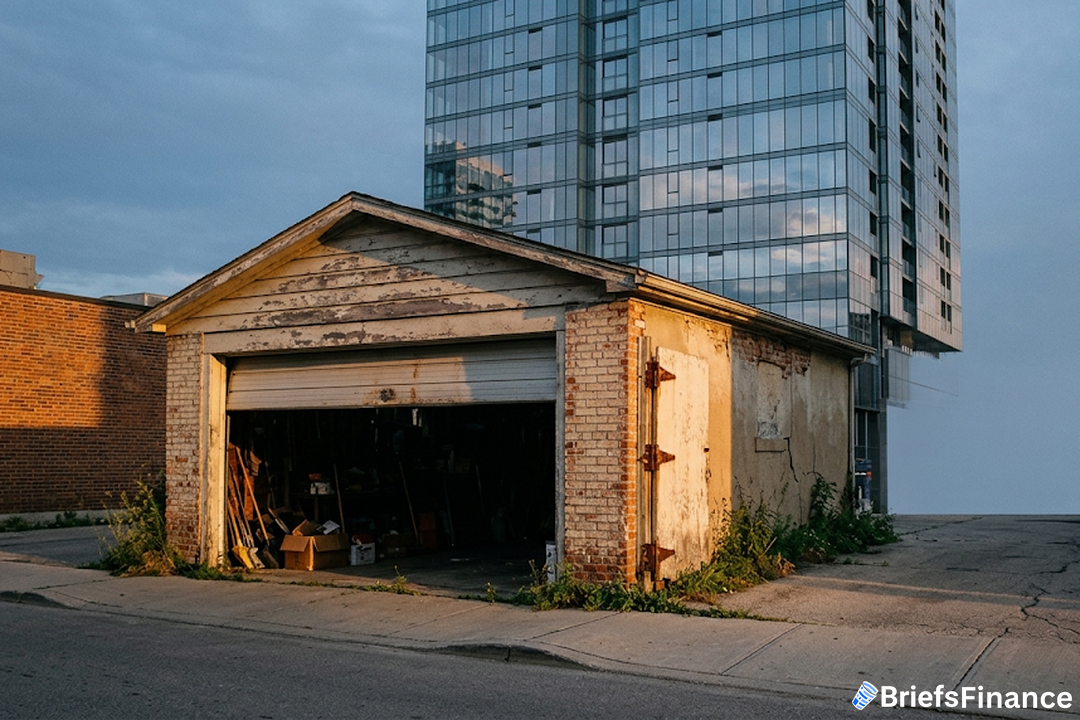
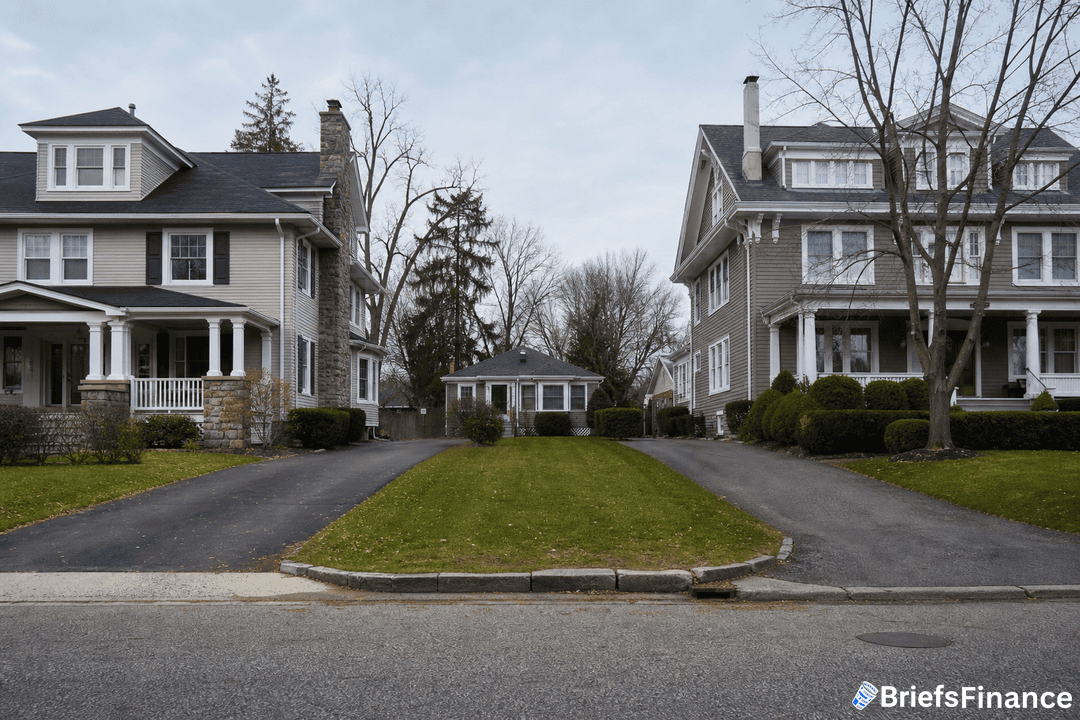
Here is the catch: the incoming supply does not line up neatly with where scarcity bites hardest. Only about 380,000 of the projected releases are two bedrooms or fewer. Nearly three quarters are three or four bedrooms, with millions more in the five-plus category.

Relative to today's mix, the gap is striking. Averaged per year, that amounts to about 3.2% of recent starter-home listings, versus 24.7% for family-home listings and 67.2% for large-home listings. Translation: the smallest boost lands where first-time buyers feel the most pressure, while the biggest lift hits segments that may face a tougher demand test.

Affordability compounds the mismatch. In a separate May study, Realtor.com and the National Association of Realtors® found that only 23% of listings were within reach for a household with about $75,000 in income - roughly half the share seen in a balanced market. Different yardsticks - bedroom count versus price - same takeaway: more choice only helps if it meets demand.

Competition for smaller homes may remain brisk because of older buyers, too. Using movers in the American Community Survey as a stand-in for recent buyers, Xu found that around 30% of purchasers of starter-sized homes are age 60 and above. "Around 30% of buyers of starter homes are aged 60 and above, suggesting older buyers, whether downsizers or late-life first-time buyers, may compete meaningfully with younger, first-time buyers for this segment," she says.

Demographic shifts move housing supply more slowly and more surely than rates do. Market Briefs reads the housing data free every morning.

Mismatch, rates and repairs

There is a possible chain reaction that could help: more family-home inventory can make it easier for existing starter-home owners to move up, freeing those entry-level places for new buyers. Just do not bank on a quick fix. "It is important to note that this 'free-up' mechanism is a secondary channel, and it may take longer to materialize," Xu says. "The primary solution to the starter-home shortage remains more new construction."

Demand could soften even as supply loosens. Harvard's Joint Center for Housing Studies projects U.S. households will grow by 8.6 million from 2025 to 2035, a slower pace than the prior decade as aging boomers accelerate losses among older households and household formation among younger adults cools. Higher mortgage rates can narrow the buyer pool without making homes feel cheaper for those still in it. As Xu puts it, "First-time homebuyers themselves are rate-sensitive, so any net benefit from reduced competition would need to outweigh the direct cost of financing at a higher rate, which makes the mechanism unlikely to deliver a clear win in reality."

The condition of released homes matters, too. "A $700,000 home that needs $100,000 in improvement doesn't necessarily solve the affordability issue for most first-time buyers, but it does help some," says Lisa Harris, an associate at Re/Max Center in Braselton, GA.

Local fault lines and what to watch

Where these imbalances land will shape price moves. Research released in April by the National Association of Home Builders highlighted markets including Pittsburgh, Buffalo, NY, and Rochester, NY as areas where aging demographics and slower growth increase the chances that turnover will outstrip new demand. Other metros with stronger growth or more pent-up buyers may absorb the inventory older owners release. Crucially, it is not just how many homes arrive, but whether each market has enough buyers who want - and can afford - those specific homes.

In Las Vegas, agent Bob Little is already seeing those forces collide. "I don't think baby boomer turnover by itself is going to dramatically change affordability," he says. "Interest rates and overall buyer demand are still much bigger factors in our market."

From here, Xu says the tell will be whether relief higher up the ladder spreads. "What we'll be watching for instead is whether family and large homes continue to see real relief as projected, and whether that relief stays contained to those segments or eventually spill over to ease pressure on entry-level buyers as well," she says.

What does this mean for your money? Expect the shake-up to hit bigger homes first. Entry-level relief will likely hinge on new construction, mortgage rates, renovation costs, and whether your local market has the right buyers for the right homes at the right prices.

A wave of listings only helps if it lands where buyers actually are. Get the free Market Briefs daily newsletter and follow the mismatch.

Disclosure

Recent News

1 2 3 … 133

Get Market Briefs delivered to your inbox every morning for free!

No fluff. No noise. No politics. Just finance news you can read in 5 minutes.

Blogs

November 20, 2026
Anthropic Stock at $1.5 Trillion: Why This IPO Isn't Amazon in 1997

Anthropic has gone public at a valuation of about $1.5 trillion, while Amazon went public in 1997 at around $440 million. Anthropic has about $33 billion in revenue this year and no profit, and investors are paying more than 40 times its sales, against about 3 times for Amazon. Briefs Finance CEO Jaspreet Singh says nobody knows what comes next, and that long-term investors use downturns to buy instead of panic selling.

Read More
November 17, 2026
Is the Stock Market Going to Crash? Why Nvidia and the Fed Have Investors on Edge
  • Tech stocks are selling off because investors don't know who will lead Nvidia, the company that has been funding the AI industry and selling it chips.
  • Inflation has the Federal Reserve planning to raise interest rates, with a hike expected in December, and that puts pressure on homebuyers, private equity and the $40 trillion national debt.
  • Briefs Finance CEO Jaspreet Singh says nobody has a crystal ball, so his rules are to buy when markets are low, hold long term and invest only what you're willing to lose.
Read More
November 16, 2026
The $40 Trillion National Debt: Trump's 4-Part Plan to Make It Feel Smaller
  • The national debt is above $40 trillion, and the Federal Reserve has gone from sending Washington its profits to losing money.
  • President Trump's four-part plan leans on shorter-term debt, stablecoin companies buying Treasuries, a bigger balance sheet and government stakes in private companies.
  • The goal is to outgrow the debt, not pay it off, so Jaspreet Singh points investors to the seven industries where Washington wants growth.
Read More
November 16, 2026
The Fed Is Talking About a Jumbo Interest Rate Hike. It Has No Easy Way Out
  • The Fed makes its next rate decision on December 9 and is now talking about jumbo interest rate hikes of 0.5%, though one in December looks unlikely.
  • Washington will pay a record $1.05 trillion in interest this year on $40 trillion of debt, and that debt resets at higher rates as the Fed hikes.
  • Jaspreet Singh's five moves are to pay down variable-rate debt, earn interest on your savings, know which stocks feel the pressure, look at value and hedge.
Read More
November 16, 2026
Buying on Margin Is at a Record High. Here's the Risk for the Stock Market
  • Margin debt, the money investors borrow to buy stocks, is at a record of around 4.6% of GDP, up from 3.9% in 2021.
  • ETF money has more than tripled in five years to 7% of GDP, while corporate buybacks and 401(k) money sit below their earlier peaks.
  • Margin calls and panic selling can make the next downturn deeper, so Jaspreet Singh keeps buying broad market funds and says most investors should skip margin debt.
Read More
November 16, 2026
Housing Prices Are Falling. Buying a House Still Isn't Cheaper
  • Housing prices have fallen for four straight weeks, but mortgage rates around 7.2% keep the monthly payment about where it was in 2023.
  • Talk of a jumbo Fed rate hike and a plan to sell Fannie Mae and Freddie Mac on the stock market could both push mortgage rates higher.
  • Briefs Finance CEO Jaspreet Singh treats a house as a liability: buy within your budget and let your investments build the wealth.
Read More
November 14, 2026
Nvidia News: Jensen Huang Is Out, and the "Bank" Behind American AI Just Lost Its Founder
  • Jensen Huang is out at Nvidia over affairs with multiple people, and the company he founded has been the bank of American AI, with about $30 billion into OpenAI and $10 billion into Anthropic.
  • A hotter-than-expected inflation report has Fed officials talking about a possible 0.5% hike in December, and gold, silver, and bitcoin fell on the news.
  • President Trump said the US may not need a deal with Iran, keeping oil prices and inflation risk high. Jaspreet Singh breaks down what it all means for AI stocks and your portfolio.
Read More
November 14, 2026
Record Highs, a 57-Year Low in Jobless Claims, and a Stock Market Bubble: Inside the Weirdest Market in History
  • Stocks are booming at the fastest pace in years, jobless claims just hit a 57-year low, and most investors still feel like nobody is hiring.
  • The Fed is protecting the dollar over the economy, oil swings on every Iran headline, and a few AI companies are carrying an S&P 500 where four of five stocks sit in a correction.
  • Jaspreet Singh explains why circular financing between Nvidia, OpenAI, Anthropic, and SpaceX rhymes with 2008's house of cards, and how his three investing pillars handle a stock market bubble.
Read More
November 14, 2026
Is a Recession Coming? The Fed Just Made a U-Turn It Has Only Made Twice in 60 Years
  • The Fed has raised rates, cut them, then raised them again only twice in the last 60 years, and both times the economy fell into a recession and stocks crashed.
  • The same stop-and-go cycle is playing out now, with one big difference: US debt is 125% of GDP today versus about 30% in 1980.
  • In the 1970s gold rose roughly 24x, real estate 157%, stocks lagged, and cash lost half its value. Jaspreet Singh lays out five assets to consider before the next flip.
Read More
November 14, 2026
The 2027 Tax Brackets Are Out: How Some Investors Can Earn $135,300 and Pay $0
  • The IRS 2027 tax plan keeps the same seven rates but widens every bracket and lifts the married-filing-jointly standard deduction to $33,200.
  • The 0% long-term capital gains bracket rises to $102,100, so a household living on $135,300 of investment income could owe $0 in federal income tax.
  • C corporations still pay 21%, small businesses keep the 20% QBI deduction, and the 401(k) limit climbs to $25,500 with an $8,500 catch-up for investors over 50.
Read More
1 2 3 … 33
Share via
Copy link