Free NewsletterPro Login
Free Live Investors Workshop
Seats limited
Tue, Sep 29.
The dollar is losing value.
Here’s how investors can still profit.
Hosted By
Jaspreet Singh
Founder, Briefs Finance
X

Warning: Undefined variable $stocks in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 448

Warning: foreach() argument must be of type array|object, null given in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 448

Warning: Undefined variable $funds in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 472

Warning: foreach() argument must be of type array|object, null given in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 472
/* the link was here */

National Home Values Fall 0.4% in June, Sharpest Monthly Decline Since Late 2022

Published Jun 30, 2026
Share:
Summary:
  • National home values dropped 0.4% from May to June, the largest monthly fall in three and a half years.
  • Sydney prices plunged 1.2% in June, dragging the national average lower, while Perth and Darwin posted gains.
  • The Reserve Bank of Australia raised interest rates by 75 basis points at its first three meetings of 2026, and new government laws tightened tax breaks for property investors.

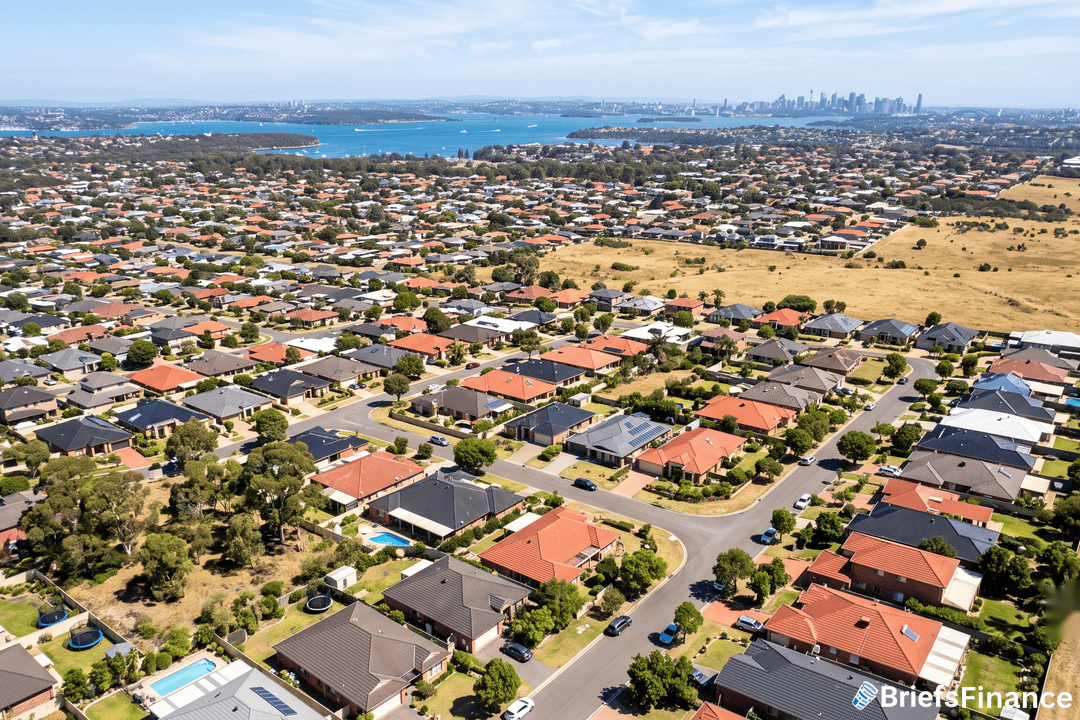
Australia's housing market just posted its worst month in three and a half years. Yet the story is not the same everywhere. Sydney and Melbourne are falling, but Perth and Darwin are still climbing.

The Numbers: A Split Market

The national home value index dropped 0.4% in June, according to property consultancy Cotality. That is the biggest monthly slide since December 2022. Sydney led the decline with a 1.2% fall, followed by Melbourne at 1%.

Adelaide flatlined. Perth rose 0.7%, and Darwin jumped 1.4%.

The median Sydney home is now worth A$1.3 million - about US$900,000. Nationally, the median price sits around A$1 million, which is 74% higher than a decade ago.

Get your free investing masterclass bonus when you join Market Briefs, our free daily newsletter

Why the Market Is Turning Lower

Three forces are pushing prices down. First, affordability was already stretched. Tim Lawless, research director at Cotality, noted, "Even before interest rates rose by 75 basis points, we were seeing affordability hurdles weighing on buyer demand."

Second, the Reserve Bank of Australia (RBA) raised rates by a total of 75 basis points over its first three meetings of 2026. These increases have severely limited how much potential buyers can borrow. Third, the Australian Labor government passed laws that limit tax breaks for housing investors and increase capital gains taxes. Lawless described the combination as "higher cost of living pressures, deeply pessimistic sentiment and a further dampening of demand via property taxation changes." These new rules reduce the incentive for investors to buy, especially in expensive cities like Sydney and Melbourne.

What This Means for Buyers, Investors, and Politics

If price declines continue, young Australians might find it easier to buy. Rents have also surged - up almost 42% in major cities over the past five years. Sydney's median house rent is A$883 per week; apartments rent for A$783.

The government hopes its tax changes will reduce support for the far-right One Nation party. But falling prices have a downside. Homeowners lose paper wealth, which could slow consumer spending. The RBA has noted this risk - a significant weakening in housing markets might hurt consumption growth.

Cotality's revised data show home prices peaked nationally in March 2026. "This reflects a market that is changing rapidly," Lawless said. "Most regions have seen values revise lower over recent months, with the largest downgrades occurring in Perth and Brisbane."

The March 2026 peak now appears to be a pivotal turning point, with most regions having since revised lower.

What to Watch

Watch how far Sydney and Melbourne fall - if the slump accelerates, the RBA may face pressure to cut rates sooner to protect the economy. But for now, the trend is downward, and a quick rebound looks unlikely. The data from June marks a clear turning point.

Subscribe to Market Briefs, our free daily newsletter, and claim your bonus investing masterclass

Disclosure

Recent News

1 2 3 … 88

Get Market Briefs delivered to your inbox every morning for free!

No fluff. No noise. No politics. Just finance news you can read in 5 minutes.

Blogs

September 29, 2026
Why Is Gold Going Down? A 5.2% Treasury Yield Just Took Its Job
  • President Trump rejected Iran's deal to reopen the Strait of Hormuz, oil prices jumped back up, and gold fell instead of rising.
  • Treasury yields hit their highest level in more than 20 years, so investors sold gold and bought Treasuries that pay interest.
  • Higher Treasury yields make the national debt, mortgages, car loans, and credit cards more expensive, with the Fed's next rate decision due October 28.
Read More
September 28, 2026
The Strategic Bitcoin Reserve: Why the Government Wants Bitcoin to Explode
  • The US government holds about 328,000 Bitcoin, worth roughly $25 billion, and since a 2025 executive order it keeps seized coins instead of selling them.
  • Washington wants a bigger pile of assets so its $40 trillion national debt looks smaller next to them, which lets it keep borrowing and spending.
  • Bitcoin's wild price swings, and a government holding a coin built to escape governments, are the two risks investors need to watch.
Read More
September 25, 2026
BRIEFS EXCLUSIVE: 43% Of Respondents Say Bills Outran Their Income Over Past Two Years
  • 43% of the 494 Market Briefs readers surveyed said their bills grew faster than their income over the past two years, even though 79% could cover a surprise $5,000 expense tomorrow.
  • Half of readers own gold or crypto, the two classic bets against a weaker dollar, and only 13% bought nothing at all in the last 12 months.
  • The median reader says it takes $150,000 a year to feel financially secure, about $62,000 above the U.S. median household income.
Read More
September 25, 2026
The Economy Is Booming. So Why Did Stocks and Bonds Fall Together?
  • S&P Global says the US economy is growing at its fastest rate since 2021, with corporate profits up 28.9% in a year, almost four times the historical average.
  • Stocks and bonds fell at the same time, which is not how the two markets normally behave, because Treasury yields above 5% now compete with stocks for investors' money.
  • Jaspreet Singh lays out three ways to invest through a shift like this: always be buying, buy the crash, or follow the money before it hits the headlines.
Read More
September 24, 2026
The 2026 Economic Reset Is Starting: Are We in a Recession, or Is the Pain Still Ahead?
  • The Federal Reserve has flipped from stimulating the economy to fighting inflation with higher interest rates, while the White House still wants growth at almost any cost.
  • The national debt tops $40 trillion, has outgrown the entire U.S. economy, and its interest payments are now the government's fastest-growing expense.
  • Higher rates bring pain for private equity, private credit, and speculative assets, but they open opportunities for investors holding cash, treasuries, and value assets.
Read More
September 23, 2026
Are We in a Recession? Without AI, America Might Already Be in One - and Washington Knows It
  • The White House attributes about three quarters of U.S. economic growth to AI, and many believe the economy would already be in a recession without it.
  • Washington has three reasons it cannot let the AI boom slow down: staying the world's superpower, outgrowing $40 trillion in national debt, and protecting a government stock portfolio worth billions.
  • Every market goes through booms and busts, and investors who understand the cycle get to buy the downturn instead of panic-selling with the crowd.
Read More
September 22, 2026
Will Interest Rates Go Down in 2026? Where the Money Moves Either Way
  • The Fed is leaning toward higher rates to fight 4% inflation, while the White House and a cracking job market push the other way.
  • If rates rise, money has tended to move toward short-term Treasuries, floating-rate loans, energy, banks and dividend payers.
  • If rates fall, it has tended to move toward gold, silver and Bitcoin, real estate, small caps, the S&P 500 and speculative bets.
Read More
September 21, 2026
How the Federal Reserve Makes Money - and Why It Just Posted Its Biggest Loss Ever
  • For 109 years the Federal Reserve created money, lent it to the U.S. government and handed the interest it collected back to Washington - almost $1 trillion in the decade starting in 2011.
  • Pandemic-era lending locked the Fed into earning about 2% on trillions of dollars while it now pays banks around 4%, producing a record loss of hundreds of billions in 2026.
  • The Fed covers its losses by creating money and the government covers its lost revenue by borrowing, and both feed the inflation that eats at the dollars in your account.
Read More
September 18, 2026
Kevin Warsh Just Defied Trump: What the Fed Rate Hike Means for Your Money
  • The Fed raised rates for the first time since 2023 in a unanimous vote led by Kevin Warsh, the chairman President Trump appointed to cut them.
  • Higher rates make the $40 trillion national debt, business loan resets and mortgages more expensive, but they strengthen the dollar and pay investors holding cash.
  • The war with Iran is pushing up oil, grocery and chip prices, another hike is likely in 2026, and recession talk is about to get louder.
Read More
September 17, 2026
Why America Bailed Out the Yen: The Japan Carry Trade, the Dollar and Your Mortgage Rate
  • In July 2026 the US sent money to steady the yen because Japan is the largest foreign owner of US debt, and Washington needs Japan to keep lending.
  • For decades the Japan carry trade let Wall Street borrow yen at essentially 0% and pour it into US stocks, real estate and Treasuries, and rising Japanese rates are shutting that off.
  • A weaker yen means fewer buyers for the dollar and for US debt, which pushes Treasury rates up and drags mortgage, car loan and credit card rates up with them.
Read More
1 2 3 … 27
Share via
Copy link