Free NewsletterPro Login

Warning: Undefined variable $stocks in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 448

Warning: foreach() argument must be of type array|object, null given in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 448

Warning: Undefined variable $funds in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 472

Warning: foreach() argument must be of type array|object, null given in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 472
/* the link was here */
×
Free investor livestream — Nov 17

How To Use ChatGPT & Claude To Research Stocks Like A Pro

01
The prompt we use to break down any stock
02
How to fact-check what AI tells you
03
How to compare two stocks in minutes

Study Finds Homeowners Insurance Strain Concentrated In Urban Cores

Published Sep 21, 2026
Share:
Summary:
  • USC's Matthew E. Kahn and Wesley A. Miller built a Local Insurance Strain Index from ZIP code data spanning 2018 to 2022 to track pressure in the homeowners market.
  • Their dataset covers about 70% of ZIP Code Tabulation Areas and roughly 87% of Americans, and shows strain is most intense near downtowns, with premiums 39% higher and insurer nonrenewal rates about 20% higher than in suburbs situated beyond five miles.
  • A one-standard-deviation increase in insurance strain corresponds to a 10.6% drop in single family home prices, a 3.1% decrease in multifamily rents, and near downtown is associated with a 19.1% fall in single family prices.

How the researchers measured insurance strain

University of Southern California economists Matthew E. Kahn and Wesley A. Miller created the Local Insurance Strain Index, or LISI, using ZIP code level data from 2018 through 2022. LISI combines three dimensions of homeowners insurance stress: affordability, measured as premiums compared with homeowner income; availability, gauged using insurer nonrenewal rates; and profitability, tracked as paid losses relative to premiums. Most of the underlying information comes from the Treasury Department's Federal Insurance Office.

Coverage is broad, spanning about 70% of ZIP Code Tabulation Areas and roughly 87% of the U.S. population. At a national view, places facing hazards like wildfire, tornadoes, and floods tend to show steeper premiums relative to income and greater challenges keeping coverage in place.

The urban pattern inside metros

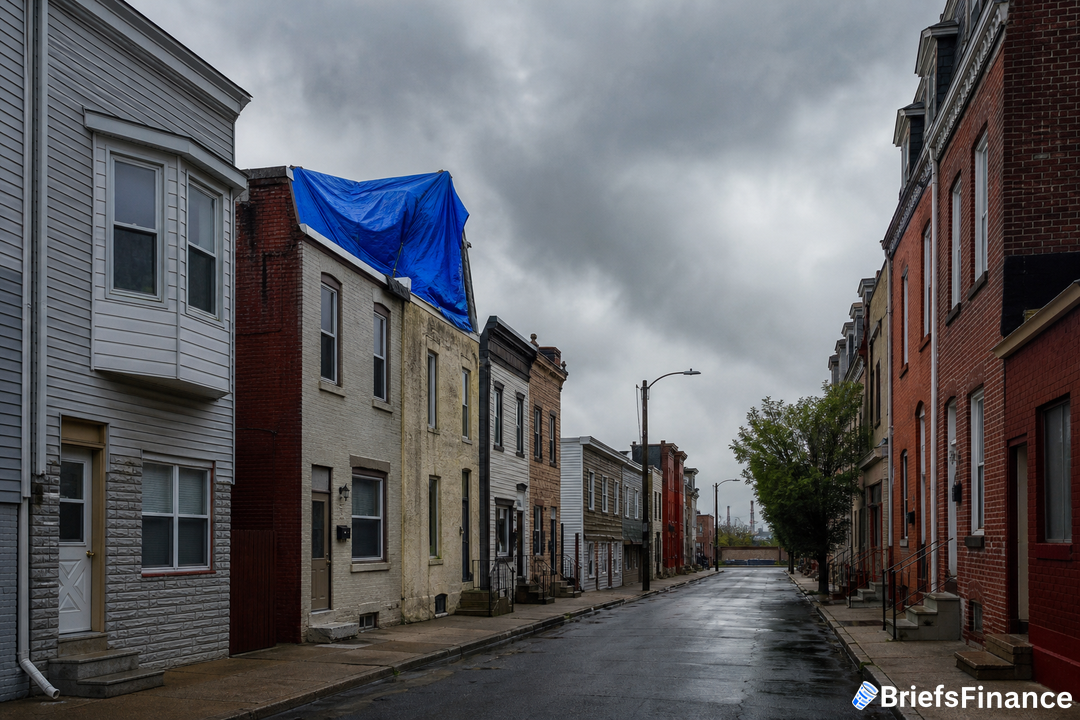
Looking within metro areas, environmental exposure typically rises as you get farther from the main business district. Yet insurance strain moves the other way. It peaks in the city center, falls quickly within roughly five miles of downtown, then stays relatively steady across the suburbs. Inside the same metro, ZIP codes close to the core experience insurer nonrenewal rates about 20% higher than suburbs located more than five miles out, and average premiums in core ZIP codes run 39% higher than those suburban areas.

Those gaps are not the result of outsized insurer profits in cities. Paid loss ratios look broadly similar between urban and suburban ZIP codes, which points to higher urban premiums tracking with higher losses rather than extra margin for insurers.

Why city insurance costs can run hot even with lower measured hazard

The study highlights risks that usually sit outside the climate conversation. Theft and burglary show up more often in dense areas. Older housing stock can drive more claims tied to plumbing, appliances, and building systems. Repairs in cities can also be pricier due to higher labor and materials costs, stricter building codes, and the complexity of working on older structures.

Insurance market design can widen the gap. In many places prone to disasters, public programs shoulder some of the biggest catastrophe exposures. The National Flood Insurance Program covers flood risk, state windstorm pools target wind, and state FAIR Plans help with other environmental perils.

Rising local risks remind investors to review how they protect and grow savings. Join Briefs Finance CEO Jaspreet Singh on September 29th for a FREE live investor workshop, How to Profit From A Dollar That's Losing its Value, where he shows how we're spotting investment opportunities as the dollar falls. Save your spot.

These backstops matter a lot in some suburban and outlying communities, including wildfire zones in California and coastal stretches of Texas and Florida. Urban owners, however, typically do not have parallel public programs for risks linked to dense living, older structures, crime, and expensive repairs. The result is an imbalance where policy helps spread catastrophe costs, while many city specific risks remain squarely in the private market.

What it does to housing values, and what that means for your money

The authors test whether local insurance strain shows up in home values and rents, and they find strong links. In ZIP codes with both home price and rent data, a one standard deviation increase in strain lines up with a 10.6% decline in single family home prices and a 3.1% drop in multifamily rents. The price to rent ratio falls 7.5%.

The pattern is most pronounced near the core, with the same increase in strain tied to a 19.1% slide in single family prices and a 6.2% drop in multifamily rents. These relationships fade with distance and are close to zero by around 30 miles from downtown.

The authors stress these are relationships, not proof that insurance strain alone moves prices or rents. Insurance strain can reflect local factors such as crime, building quality, or other environmental downsides that also shape housing demand. Still, two mechanisms fit the data: higher premiums and patchier coverage increase the cost and uncertainty of owning, which trims what buyers will pay for single family homes, and the underlying local conditions that trigger claims can make an area less appealing for both owners and renters.

Their takeaway reframes today's insurance crunch as a within metro story. A big share of homeowners losses comes from non environmental risks concentrated in city centers. So efforts to ease urban housing affordability should weigh insurance affordability and availability when considering tools like rate regulation, residual market expansion, and zoning. What drives the cost to insure property in cities are local factors - crime, the makeup of the building stock, infrastructure, and the liability climate - that often sit beyond standard insurance policy levers.

What this means for your wallet: insurance pressure is showing up the most in central city ZIP codes and is visible in nearby home values and rents, with the effect tapering as you move outward. If you keep tabs on urban real estate exposure, insurance strain is a local variable worth watching.

Keeping a steady plan helps your wealth weather changes in housing and insurance. Our CEO Jaspreet Singh is hosting a FREE live investor workshop, How to Profit From A Dollar That's Losing its Value, on September 29th. Sign up free to join him live.

Disclosure

Recent News

1 2 3 … 125

Get Market Briefs delivered to your inbox every morning for free!

No fluff. No noise. No politics. Just finance news you can read in 5 minutes.

Blogs

November 3, 2026
How to Budget Every Payday: 5 Moves So You Never Worry About Money
  • A median earner could make about $4.7 million over a career, yet most retire with closer to $13,000 in the bank because of a keeping problem, not an income problem.
  • Audit your money, save $2,000, pay off credit card debt, then automate a 75/15/10 split across three bank accounts.
  • Earn more only after your system is in place, then protect what you build with an accountant, attorneys, the right insurance, and an estate plan.
Read More
November 3, 2026
How to Invest in Stocks: 5 Things to Do Before You Invest Your First Dollar
  • Paying off credit card debt at around 22% interest beats the stock market's roughly 10% average, and even Warren Buffett's 19%.
  • Save $2,000 in a separate emergency fund, learn to research with AI, and decide whether you're a growth, income, or wealth preservation investor.
  • Write down a plan for buying during market crashes, which have happened 25 times in the last 100 years.
Read More
November 3, 2026
Best ETFs to Buy: 5 Three-ETF Portfolios for Every Investing Goal
  • An ETF is a basket of stocks, so one purchase spreads your money across many companies instead of riding on just one.
  • Jaspreet Singh laid out five portfolios of three ETFs each, built for kids, cash flow, growth, slow and steady growth, and protection from a weaker dollar.
  • Based on 10-year average returns, $500 a month could grow to between about $660,000 and $3.1 million over 30 years, though past returns never guarantee future ones.
Read More
November 3, 2026
Best Investments of a Generation: 5 Market Shifts Backed by Your Tax Dollars
  • Private companies are about to spend $1 trillion a year on AI, and the Trump administration is putting tax dollars behind the same industries.
  • The five shifts are AI and its supply chain, robotics, rare earths, energy, and defense.
  • Each comes with real risk, from an AI bubble to wars ending or a new Congress, so these are ideas to research, not sure things.
Read More
November 3, 2026
How to Get Ahead Financially: 10 Moves to Make While Everyone Else Falls Behind
  • Learning a high-income AI skill, or building AI tools for tradespeople, can raise your earning power in a tough job market.
  • Higher interest rates, the 2025 tax cuts, Trump accounts, and stacked cash back can put more money back in your pocket.
  • Following where government money is moving, keeping cash ready for market crashes, and investing in your own education can speed up your wealth.
Read More
November 3, 2026
National Debt at $40 Trillion: Why Inflation Is the Hidden Tax, and Who Profits From It
  • Time magazine asked President Trump how he'd tackle the $40 trillion national debt, and he suggested inflation could help pay it off, a cost that lands on everyday Americans.
  • From 1971 to 2025, cars, houses, and college outpaced both inflation and incomes, while the S&P 500 grew more than 33,000% with dividends reinvested.
  • The U.S. can default, inflate, or outgrow its debt, and history shows each path rewards different assets.
Read More
November 3, 2026
FOMC Meeting: Why the Fed Is Getting Nervous, and Why AI Stocks Feel It
  • At its latest meeting, the Fed held rates steady but warned it may raise them again, because inflation is running near 3.5% against a 2% target.
  • Oil prices, tariffs, AI's hunger for energy, and government spending are all pushing prices higher, and gold, silver, and bitcoin fell on the Fed's news.
  • Chinese AI stocks are down about 40% in a few months and Google fell more than 10% in a day, raising fears that higher rates could pop an AI bubble.
Read More
November 3, 2026
Midterm Elections: Where the Money Could Move if Republicans or Democrats Win
  • The U.S. government spent about $7.5 trillion last year, and the midterm elections could change which industries get more of that money.
  • A Republican win could favor manufacturing, fossil fuels, banks, and defense.
  • A Democratic win could favor healthcare, weight-loss drugs, clean energy, and infrastructure.
Read More
November 3, 2026
Brazil Stock Market Crash: Why Lula's Win Matters to U.S. Investors
  • Brazil's stock market fell more than 20% in a few days, and its currency dropped 8%, after Lula won a presidential election investors expected him to lose.
  • The shock reaches U.S. investors through coffee and beef prices, the BRICS push away from the dollar, and a market that had become an investor favorite.
  • The last time Lula first won, in 2002, Brazil's stock market fell more than 20% and then grew 12x by 2008, though nobody knows if that will repeat.
Read More
November 2, 2026
Credit Utilization: How Paying Down Cards Can Help Your Score
  • Credit utilization is your card balances divided by your credit limits, checked overall and card by card.
  • Lower is generally better, and Experian says the effect becomes more noticeable around 30%.
  • Paying down balances and keeping new charges off your cards are the main ways to lower it.
Read More
1 2 3 … 32
Share via
Copy link