Free NewsletterPro Login

Warning: Undefined variable $stocks in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 448

Warning: foreach() argument must be of type array|object, null given in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 448

Warning: Undefined variable $funds in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 472

Warning: foreach() argument must be of type array|object, null given in /var/www/briefs.co/htdocs/wp-content/plugins/oxygen/component-framework/components/classes/code-block.class.php(133) : eval()'d code on line 472
/* the link was here */

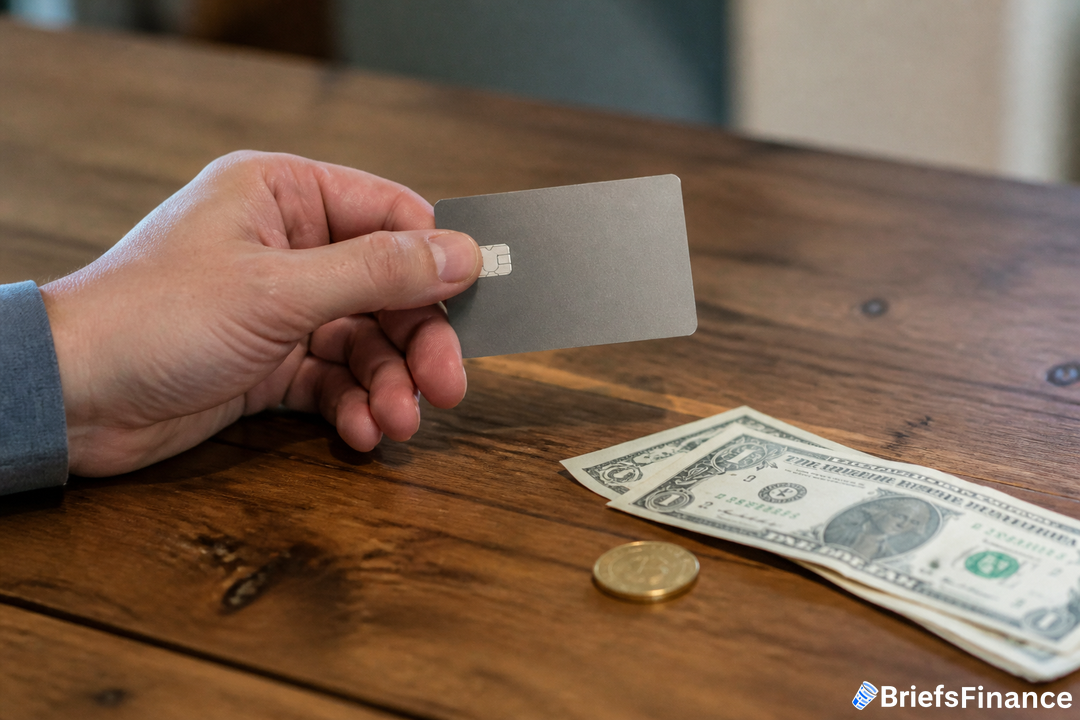
Krak Debit Card Rewards Users with Cash or Bitcoin

Published Aug 18, 2026
Share:
Summary:
  • Kraken's fintech app Krak introduced the Krak Card on Aug 18, 2026.
  • The card pays up to 2% back in cash or bitcoin, and the rate can rise with the assets a customer keeps.
  • Users can spend from more than 600 currencies or crypto assets, with chosen balances converted to dollars at checkout.

The New Card, Explained

Rewards cards have always had a catch. The best ones usually ask you to borrow money, carry a balance, or pay fees to make the points worth your time.

Krak wants to flip that deal.

Rewards are paid as actual money, not points.

The card debuted Aug 18, 2026.

You can also pick which assets get spent first and split a single purchase across several balances.

A New Kind of Rivalry

Kraken has been around since 2011 and is one of the biggest crypto exchanges in the world. Its usual clientele has been large financial institutions, seasoned traders, and those who use leverage, not casual shoppers.

It has also been rebuilding its app with new automated trading features to reach a wider audience.

The best financial decisions come from understanding the whole picture. Join Market Briefs free and get the full brief each morning.

The card takes that push much further. It puts Krak directly against Block's CashApp, PayPal's Venmo, SoFi, Robinhood, and Chime in the race to become the place where people keep and spend their everyday money.

Crypto is becoming more embedded in mainstream finance. Coinbase has claimed the role of gateway to crypto, while Robinhood has claimed the gateway to broader investing.

Kraken is leaning into its crypto-native identity. Arjun Sethi, co-CEO of Kraken's parent company Payward, frames the whole launch around trust.

"People have lost trust in how the financial system treats them, in the rates they're paid, the fees they're charged, and how rewards actually work. They're right to," he said.

The Catch Behind the Rewards

There is a reason most rich rewards sit on credit cards instead of debit cards. U.S. rules cap the interchange fees banks can collect on debit transactions, and those fees are what typically fund rewards.

A 2% reward is hard to finance from card spending alone, so the card runs through a partner bank and the real payoff comes from something else.

Kraken's bigger goal is to capture more of each customer's financial life. A debit card that pays well encourages people to hold assets on the platform, spend from those balances, and keep their money in one place.

Kraken's business already spans trading, derivatives, institutional custody, and tokenized equities. The card is another way to keep more of that activity inside its ecosystem.

Kraken also holds a banking charter from Wyoming, and this year it became the first crypto firm to receive a Federal Reserve master account, giving its banking arm direct access to core U.S. payment systems.

What It Means for Your Money

A Krak-commissioned national survey covering more than 2,000 U.S. adults found that 63% feel financially behind, and 60% said they would switch to a debit card with meaningful rewards that does not require taking on debt.

"The old deal was simple: if you wanted rewards, you had to take on debt to get them. That deal is over," Sethi said.

"The Krak Card turns whatever people choose to hold into money they can spend anywhere, and pays the value back as cash, not points," he said.

For people who already hold crypto, a card like this gives those balances a way to do the unglamorous work of paying for everyday life. For everyone else, it is another sign that the fight over your wallet now includes the assets you already own.

Kraken is positioning the card as a way to combine crypto and everyday finance. The company already has the licenses, infrastructure, and customer base to support that ambition.

Markets move every day, and most of it never reaches you in time. Get the free Market Briefs daily newsletter and stay ahead of it.

Disclosure

Recent News

1 2 3 … 104

Get Market Briefs delivered to your inbox every morning for free!

No fluff. No noise. No politics. Just finance news you can read in 5 minutes.

Blogs

October 16, 2026
How Boring Math Makes You Rich: The Briefs Money Spreadsheet, Explained
  • Briefs Money shows you what to do with every paycheck, and in what order: how much to spend, save, and invest, when to build an emergency fund, and which debt to pay off first.
  • The Climb to Wealth course walks you through the system step by step, and the Personal Finance Spreadsheet is where you track your own numbers.
  • Investing is one piece of building wealth. The system that gets money to your investments, and keeps it there, decides the outcome.
Read More
October 16, 2026
Common Investing Mistakes: Why a Stock Grade Is One Tool, Not the Whole Toolkit
  • The Briefs Score shows growth, income, and wealth preservation investors how well a stock fits their goal, with a separate letter grade for each one.
  • The most common mistake is treating the letter as an instruction. An A tells you a stock scores well for one goal, not that you should buy today.
  • Research works best as one input in a process you own. The grade shows how a stock stacks up. You supply the goal, the timeline, and the rules for being wrong.
Read More
October 16, 2026
How to Read a Company's Numbers Without a Finance Degree (Using Briefs Terminal)
  • Briefs Terminal lets you size up any public company in about ten minutes: what the stock costs, what it earns, how fast sales are growing, and what it pays you, all on one page.
  • It lines those numbers up against the company's closest competitors for you, so you can tell if a number is impressive or just average.
  • Below that are the income statement, balance sheet, and cash flow statement from the company's SEC filings, the latest news, and transcripts of its earnings calls.
Read More
October 16, 2026
What Type of Investor Am I? The Three Investor Archetypes, Explained
  • Briefs sorts its stock grades and monthly reports by three investor goals: growth, income, and wealth preservation. Pick yours and you know which report and which grade to read first.
  • Growth investors want stocks that beat the S&P 500. Income investors want to get paid in cash. Wealth preservation investors want stocks that hold up when the market drops.
  • The same stock can score an A- for one goal and a D- for another, so picking your goal comes before picking any stock.
Read More
October 16, 2026
How to Build a Stock Watchlist That Isn't Just Stocks You Heard About
  • A watchlist on Briefs Terminal lets you group stocks by the idea you're tracking and follow each one's price, one-day move, and 52-week high and low in one place.
  • Each list has its own name and description, so you always know why a stock is on it, and you can make as many lists as you have ideas.
  • The monthly growth, income, and wealth preservation reports under the Briefs Research tab hand you new themes to track that you didn't hear about online.
Read More
October 16, 2026
How to Choose an ETF That Matches Your Idea (Using the ETF Planning Tool)
  • The ETF planning tool takes an idea like "I want to invest in fast food companies," asks what you mean, and finds the ETFs that match, with the reasons, the holdings, and the sources.
  • Build a Plan then shows what your money could grow to in those ETFs over the years you choose, with conservative, expected, and optimistic estimates next to the S&P 500.
  • It gets you from an idea to an actual plan without researching dozens of companies one at a time.
Read More
October 16, 2026
Is This Stock a Good Buy? How to Use the Briefs Score to Tell If a Stock Fits the Way You Invest
  • The Briefs Score shows growth, income, and wealth preservation investors how well a stock fits their goal, with a separate letter grade for each one.
  • One stock can score very differently for each. Nvidia showed an A- for growth and a D- for income, because it grows fast and pays almost no dividend.
  • Seven sub scores under each grade show what earned the letter, so you can see exactly where a stock is strong or weak for your goal.
Read More
October 16, 2026
How to Tell an Asset From a Liability: The One Question to Ask Before You Buy Anything
  • The typical American household earned more in 2025 than in any year on record, yet only 30% of Americans say they could pay a surprise $1,000 bill from savings, so the problem isn't income but what the income gets spent on.
  • An asset puts money in your pocket and a liability takes money out, and the wealthy buy assets first, then let the assets pay for the fun stuff.
  • Before you buy anything, ask one question: does this put money in my pocket, or take money out of my pocket? Then you need a plan for the money you keep.
Read More
October 16, 2026
How to Build Your First $2,000 Emergency Fund and Wipe Out Every Debt Over 10%
  • Your first money goal isn't investing, it's $2,000 in its own account named Do Not Touch, built by moving 10% of every paycheck into it automatically.
  • More than a third of American adults couldn't cover a $400 surprise bill with cash or savings, according to the Federal Reserve, and that's how one bad day turns into years of credit card payments.
  • Once the $2,000 is there, attack every debt charging more than 10% interest, highest rate first, because you can't out-invest a 22% credit card so paying it off is the investment.
Read More
October 16, 2026
How to Invest Through a Crash: 3 Rules From the Worst-Timed Investor Alive
  • Meet Bunty, a fictional investor with the worst timing in history: he put $100,000 into the market in four chunks right before four crashes, never sold, and by 2025 it had grown to more than $500,000.
  • Investors who jump in and out of the market miss its best days, and missing just a handful of those days can cut your final result roughly in half.
  • The fix is ABB, Always Be Buying: you buy on a schedule through booms, crashes and scary headlines, which matches the market, and beating it takes knowing where the money is moving first.
Read More
1 2 3 … 29
Share via
Copy link