The growth playbook
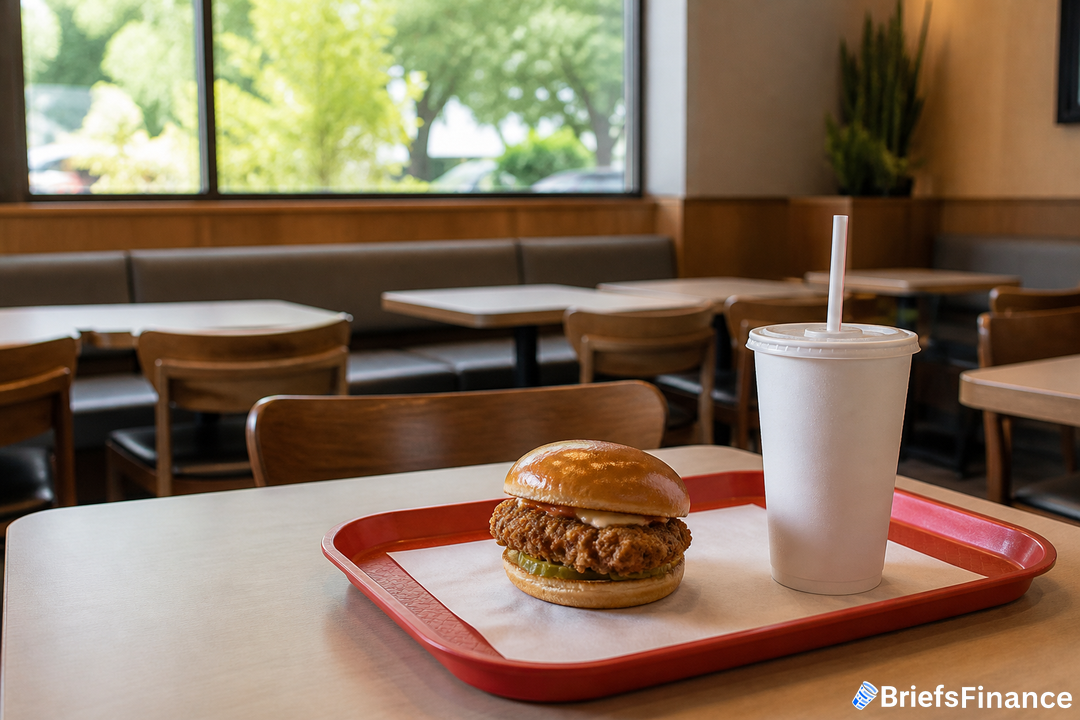
At a September investor day, McDonald's spotlighted chicken and drinks as its next growth engines to broaden beyond beef. The company set goals to lift its global presence in each by 1.5 percentage points over the next several years.
Kempczinski told CNBC, "Chicken is a $130 billion category. We have about a 20% share of chicken. Beverages is about a $230 billion category. We have a 10% share of beverages," noting there is more runway in those markets than in the roughly $50 billion global beef category where McDonald's has about 40% share.
Menu strategy is how restaurant chains defend traffic when budgets tighten. Market Briefs covers the consumer economy free every weekday.
Where its customers are spending
Exclusive data assembled by Consumer Edge using credit and debit card activity shows competition for McDonald's customers is heating up. Among those customers, Chick-fil-A picked up 0.58 percentage points of limited-service restaurant spend in the third quarter from a year earlier, the biggest increase among the chains in the dataset.
Coffee concepts are also moving up the list for these consumers. The drive-thru-only brand 7 Brew gained 0.4 percentage points, and Starbucks, Dutch Bros. Coffee and Dunkin' also landed in the top 10.
Together, those four coffee players notched a combined 0.88 percentage points increase in spending share. McDonald's still ranked as the single largest chain in overall limited-service spending by its customers, though its portion slipped year over year. Among burger peers, Restaurant Brands International's Burger King rose by 0.24 percentage points, the top improvement in that category.
"There's a big battle for a smaller amount of restaurant spend as people become more selective in what they spend," said Michael Gunther, a senior vice president at Consumer Edge. He added, "If they [McDonald's] are able to attract diners with interesting options, it could work." He also cautioned that the card data shows where money goes, not exactly what was ordered at the counter.
Momentum check and investor lens
Sales have been soft, but McDonald's executives said trends looked a bit better toward late Q3. At the investor event, the company said that in the U.S., comparable sales dipped slightly in July and August, and that it expected September to flip back to positive. Consumer Edge likewise observed that, in September, the company's year-over-year spending share erosion eased across every income group.
Wall Street is watching the timing and costs closely. Bernstein's Danilo Gargiulo said after the event that recent U.S. beverage launches had not produced enough revenue to counter broader weakness, and that the next chicken platform - including hand-breaded and grilled items - was further out than he anticipated. "The scale of investment required to deliver [the company's growth plan] McDonald's Next was above our expectations and introduces additional pressure on near-term earnings," he wrote.
Gargiulo keeps a market perform rating on the shares with a $295 price target. On Friday, the stock finished near $235.
What gets promoted tells you where the margin actually is. Join Market Briefs free and follow it.